|
Strong jobs growth masks deteriorating picture Pendal July 2026 (2-minute read) |
|
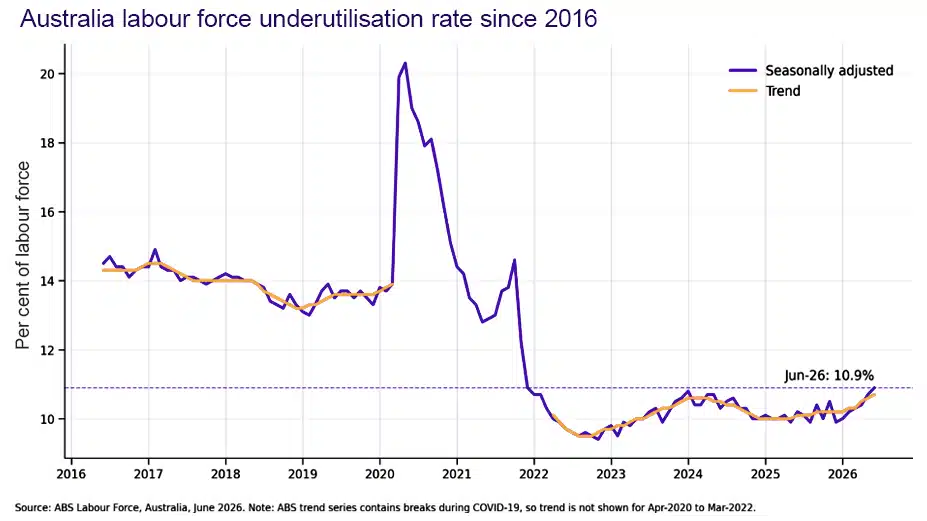
The latest jobs data has lifted market expectations for an RBA hike, but rising underutilisation suggests the labour market is gradually softening. WHILE recent times have seen a major improvement in the timeliness and accuracy of data from the Australian Bureau of Statistics (ABS), the Labour survey remains stuck in time gone by. Collection of data from the 25,000 households involves either on-line forms, telephone interviews or even face to face. The survey contains 70 questions revealing a fair bit of personal information. You stay in the survey for eight months before rotating out. Now I would not want to be the one collecting this data, as if I get a call, email or even a knock on the door from someone claiming to be from the ABS, my most likely course of action would be to avoid the scam. But apparently, they have over a 90% success rate, which may also be due to a potential fine if you don't cooperate. Collection issues aside the survey is quite volatile, so I prefer to look at trend measures when assessing the state of employment. On this basis trend unemployment is at 4.4% and trend job growth is at 0.2%, or 32,300 a month. This suggests labour supply is also increasing, both with immigration and participation (back up to 67%). The RBA expected unemployment to be at 4.2% by the end of June. They also expected employment growth to be at only 1.3%, but it has come through at 1.6%. So, more jobs than predicted but also higher unemployment. The Reserve Bank would view that as a draw, meaning no impact on inflation from either excess demand or supply. Underutilisation However, perhaps of mild concern to the Reserve Bank would be the increase in labour underutilisation. This measure looks at not only unemployment but adds in part-time workers seeking more hours, known as underemployment. It is trying to get a more accurate and earlier read on spare capacity. The recent shift to part-time job creation over full time means rising spare capacity. Underutilisation now stands at 10.9%, meaning around 1.7 million people either don't have a job or want more hours. This is historically still quite low but is hardly a sign of overall tight conditions. Importantly, it continues to deteriorate.
Market Impact Bond markets have been selling off this month largely on Middle East tensions. The most recent headline employment growth saw yields shift slightly higher and the odds of an August hike shift from 25% to 30%. The key distinction here is between nominal and real yields. The nominal 10-year yield is the visible market yield, currently around 5%, but the real yield is the return investors receive after inflation expectations. That is what matters for purchasing power. If inflation expectations remain reasonably anchored, a 5% nominal yield represents a meaningful positive real yield. This is why bonds are starting to look better value, even if the short-term mark to market remains uncomfortable. I am slightly surprised by this as the labour market seems to be steady to slightly deteriorating. However, when overnight headlines easily move markets, few participants are wanting to take on the volatility. For more patient investors, 10-year yields around 5% do offer value. If inflation expectations remain contained, that implies a positive real yield, which is the more important measure of long-term bond value. A slowly deteriorating labour market and rising underutilisation should also limit the need for further tightening. With term premium higher than normal, investors are now being paid more both for inflation adjusted return and for taking duration risk. |
|
Funds operated by this manager: Pendal MicroCap Opportunities Fund , Pendal Sustainable Australian Fixed Interest Fund - Class R , Pendal Focus Australian Share Fund , Pendal Horizon Sustainable Australian Share Fund , Regnan Credit Impact Trust Fund , Pendal Sustainable Australian Share Fund , Pendal Multi-Asset Target Return Fund , Barrow Hanley Concentrated Global Share Fund , Pendal Active Balanced Fund , Pendal Active Conservative Fund , Pendal Australian Equity Fund , Pendal Australian Long/Short Fund , Pendal Australian Share Fund , Pendal Dynamic Income Fund - Class R , Pendal Fixed Interest Fund , Pendal Global Emerging Markets Opportunities Fund - Wholesale Class , Pendal Global Property Securities Fund , Pendal Government Bond Fund , Pendal Imputation Fund , Pendal MidCap Fund , Pendal Monthly Income Plus Fund , Pendal Property Investment Fund , Pendal Short Term Income Securities Fund , Pendal Smaller Companies Fund |
|
This information has been prepared by Pendal Fund Services Limited (PFSL) ABN 13 161 249 332, AFSL No 431426 and is current as at December 8, 2021. PFSL is the responsible entity and issuer of units in the Pendal Multi-Asset Target Return Fund (Fund) ARSN: 623 987 968. A product disclosure statement (PDS) is available for the Fund and can be obtained by calling 1300 346 821 or visiting www.pendalgroup.com. The Target Market Determination (TMD) for the Fund is available at www.pendalgroup.com/ddo. You should obtain and consider the PDS and the TMD before deciding whether to acquire, continue to hold or dispose of units in the Fund. An investment in the Fund or any of the funds referred to in this web page is subject to investment risk, including possible delays in repayment of withdrawal proceeds and loss of income and principal invested. This information is for general purposes only, should not be considered as a comprehensive statement on any matter and should not be relied upon as such. It has been prepared without taking into account any recipient's personal objectives, financial situation or needs. Because of this, recipients should, before acting on this information, consider its appropriateness having regard to their individual objectives, financial situation and needs. This information is not to be regarded as a securities recommendation. The information may contain material provided by third parties, is given in good faith and has been derived from sources believed to be accurate as at its issue date. While such material is published with necessary permission, and while all reasonable care has been taken to ensure that the information is complete and correct, to the maximum extent permitted by law neither PFSL nor any company in the Pendal group accepts any responsibility or liability for the accuracy or completeness of this information. Performance figures are calculated in accordance with the Financial Services Council (FSC) standards. Performance data (post-fee) assumes reinvestment of distributions and is calculated using exit prices, net of management costs. Performance data (pre-fee) is calculated by adding back management costs to the post-fee performance. Past performance is not a reliable indicator of future performance. Any projections are predictive only and should not be relied upon when making an investment decision or recommendation. Whilst we have used every effort to ensure that the assumptions on which the projections are based are reasonable, the projections may be based on incorrect assumptions or may not take into account known or unknown risks and uncertainties. The actual results may differ materially from these projections. For more information, please call Customer Relations on 1300 346 821 8am to 6pm (Sydney time) or visit our website www.pendalgroup.com |