|
Hedge Clippings | Friday 14 June, 2019
Hedge Clippings has been known to be cautious, risk averse, glass half empty, negative even, call it what you will. Indeed, we know this not only as a result of some intense and painful navel gazing (not only painful as a result of the gazing, but also the shape of the navel) but due to some of the feedback we occasionally receive to that end.
However in our own defence - after all if we can't defend ourselves, it is left to others to defend us, and we can't always rely on them - we're firmly in the camp of always making sure that the downside is fully evaluated prior to taking risk. Sometimes this is easier said than done, which is when the rear-view mirror comes in handy, but essentially investing success is as much the result of not losing one's capital as it is making great returns.
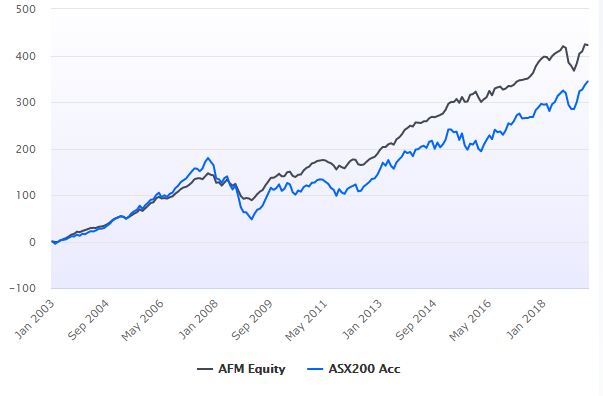
That possibly explains our preference for those hedge and absolute return funds, which might not shoot the lights out in bull markets, but aim to protect investors' capital when it matters most. By and large, and taken on the average, this has proven itself over the years as shown in the chart below, where since 2003 equity funds in AFM's database have significantly outperformed the ASX200 Accumulation Index mainly by avoiding the latter's drawdowns:
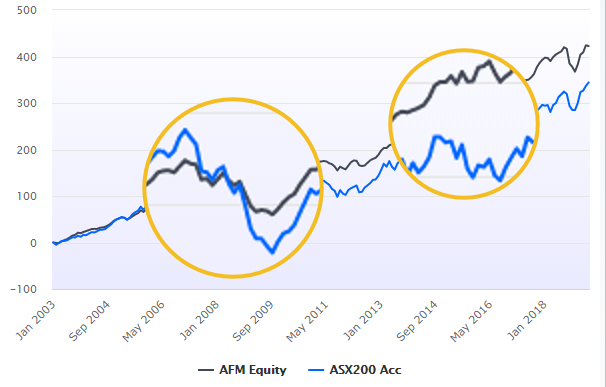
As highlighted below, this is particularly evident from October 2007 to February 2009, and again from February 2015 to February 2016:
However this logic has been sorely tested over the past 12 to 24 months, particularly in the last quarter of 2018 and the first quarter of this year when the correlation between the ASX200 Accumulation Index and AFM's Average Equity Index became unusually high.
Much of this can be attributed to the vagaries of US Fed policy and 10 year bond yields, which in September last year were expected to reach 3.5% (this making US equities judged by the S&P500 with an average yield of just 2% look expensive) prior to a policy reversal which now sees 10 year bonds at 2.11%, and the 30 year yield at 2.59%.
Fund managers and investors who had struggled to reset portfolios in the last quarter of last year were then faced with a double whammy as markets reversed in the first quarter of this year. Not easy therefore for "momentum" investors, while the issue for many "value" investors is that it is difficult to find value at historically high PE's, or amongst tech or new economy stocks with great forward estimates but negative earnings.
The investment outlook is being clouded by doubt - doubt about economic issues such as growth, interest rates, inflation, low wages growth and employment, all overlaid by geo-political and trade tensions as a result of the Trump-Xi trade tussle, Brexit, and China (where the latest monthly auto sales fell over 16% y-o-y), be it demonstrations on the streets of Hong Kong, Taiwan, or the control of the South China Sea.
Closer to home, employment rose last month by an unexpectedly high 42,300 in May, of which only 2,400 were full time jobs, and April's number was revised upwards from 28,400 to 43,100. However, unemployment is locked firmly at 5.2% - some of that is possibly election related. Consumer and business confidence are showing little correlation either - again possibly election related.
The RBA has focussed on employment and inflation, and it seems likely therefore that the market is correct in forecasting further rate cuts in official rates to 1% or even less, but that in itself won't fix the economy - in fact the reduction in deposit rates will curb consumer spending further.
It's not to say there aren't opportunities. In spite of all the above, Hedge Clippings is not pessimistic. However, we think we can - and should - be excused for being cautious.
|


