


Macro risk and volatility remain front and centre
Macro issues seem to be centred on geopolitical risk, particularly where The Donald is involved. Mind you, his "my button is bigger than yours" policy approach seems to be moving things along on the Korean Peninsula more than those of his predecessor, so while his style may be more "hardball" than "diplomatic", it might just also turn out to be more effective.
Syria, and in particular with Russia and Iran's involvement, may be a harder nut to crack. From a market perspective investors are possibly becoming acclimatised to Trump's Twitter Diplomacy, which in itself may be a risk when, or if, the rhetoric results in an actual physical or military confrontation.
Meanwhile turning to the markets, in spite of the increased volatility of the past two months, the upcoming US earnings season is likely to see continuing growth in positive numbers. As the US economy picks up, and while wages/inflation remain reasonably benign, interest rates rises will remain firmly on the agenda as the market's number one economic risk.
What has recently changed in the US is the market's perception and realisation, particularly over the issue of privacy and personal data for tech stocks and the FANGS, which have had such a stellar run for the past few years. Suddenly people are realising that if you're not paying for a service or product, you are the service or product.
Meanwhile taking a look at the local market and funds' performance YTD and over the past 12 months, where apart from January in the US, there is a sea of red:
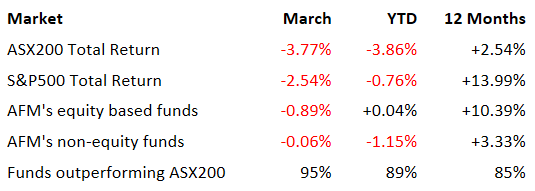
Hedge and absolute return funds risky? Hardly! Although choppy markets certainly make things more difficult in a general sense, equity based funds' average outperformance of almost 8% over 12 months, with 85% of all funds' returns beating the market, would seem to answer their critics.
Next week sees a recommencement of the Hayne Royal Commission, with the spotlight turning to the Financial Services sector and wealth advice (or more correctly in some cases, lack of it). Whilst unlikely to be quite as explosive as envelopes stuffed with cash passing across the desks of suburban bank managers' desks, it will still cause plenty of embarrassment to those in the spotlight, and others in the advice industry.
Expect particular attention not only on fees being charged with no advice given, but also over promotion of in house products on dealer groups' approved product lists (APL's), and vertical integration of the industry overall.
