


NEWS

1 Jun 2026 - Manager Insights | Digital Asset Funds Management
|
Chris Gosselin, CEO of FundMonitors.com, speaks with Clint Maddock, Director and Co-Founder at Digital Asset Funds Management. Clint discussed how the fund has remained profitable despite Bitcoin's recent decline, highlighting its market-neutral arbitrage strategy across multiple digital asset exchanges. He also shares his outlook on crypto market catalysts, including regulatory developments in the US, and the fund's growth following its distribution partnership with Montgomery Funds Management.
|

28 May 2026 - Good intentions. Unintended outcomes?

26 May 2026 - AI needs more than chips: Why power and grid buildout matter

25 May 2026 - 10k Words | May 2026
|
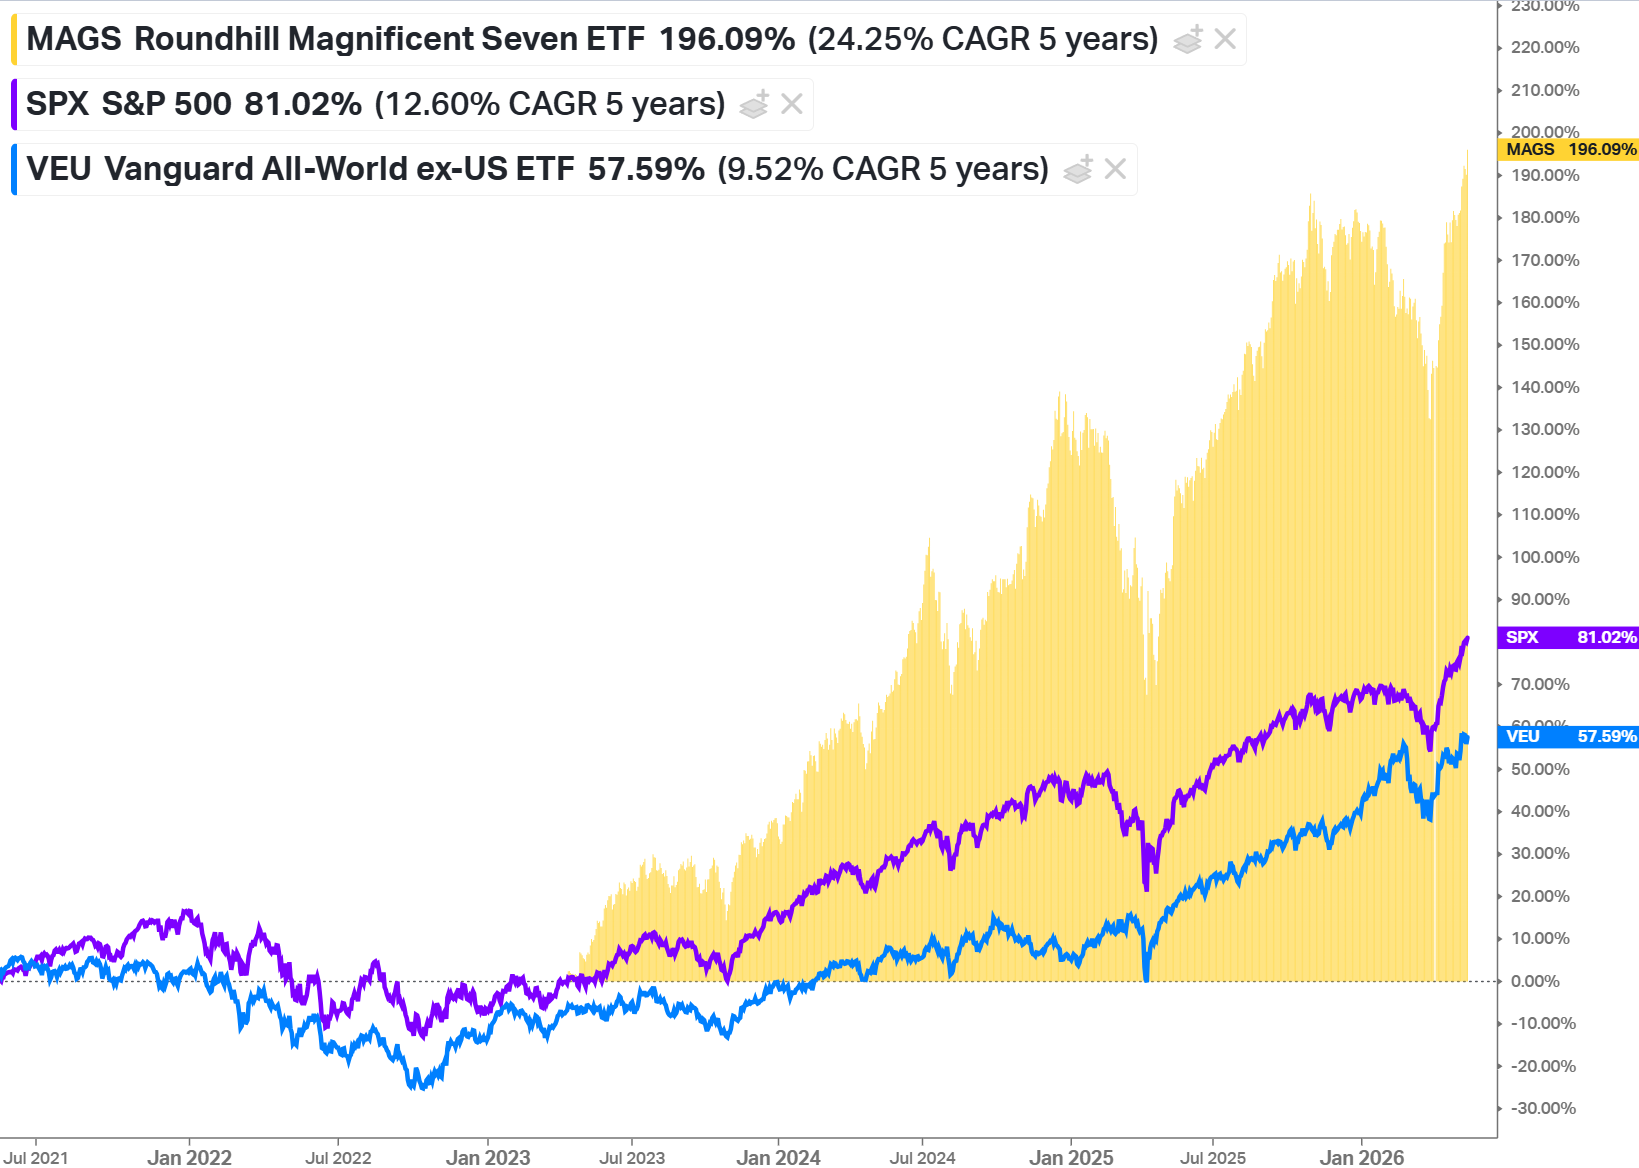
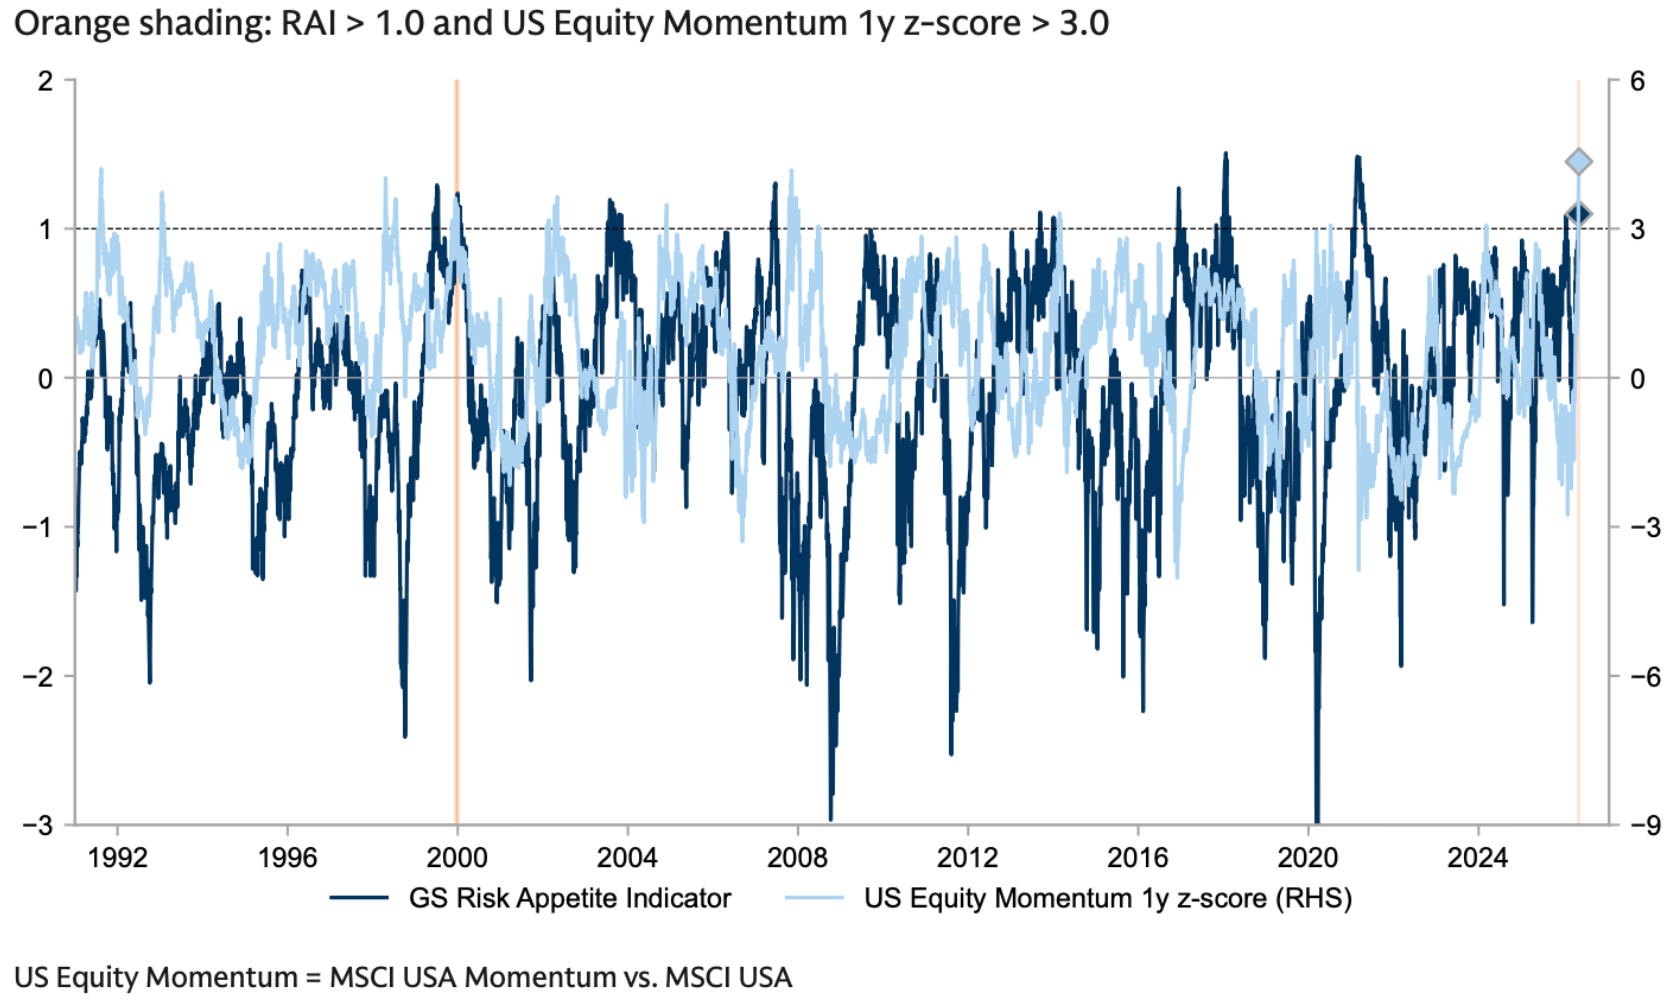
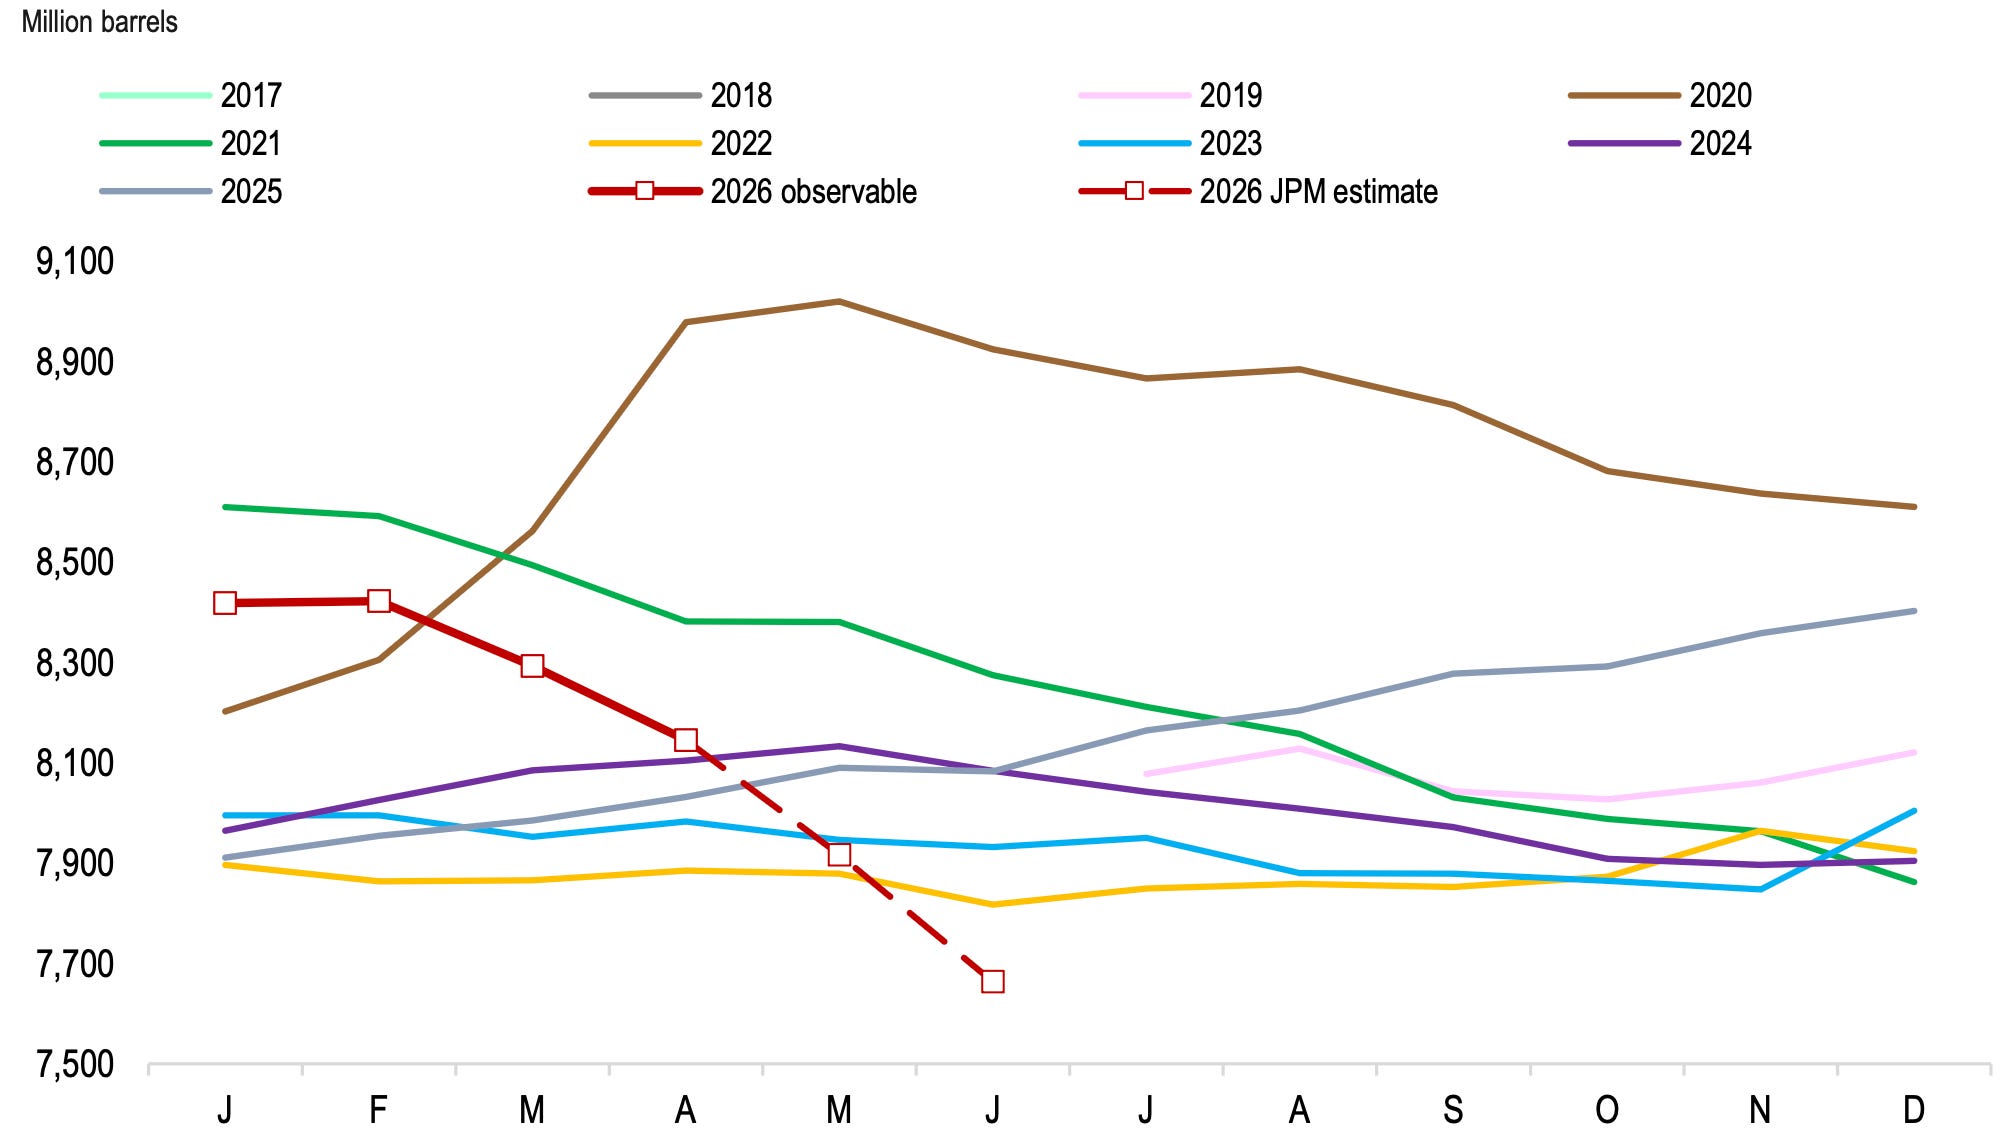
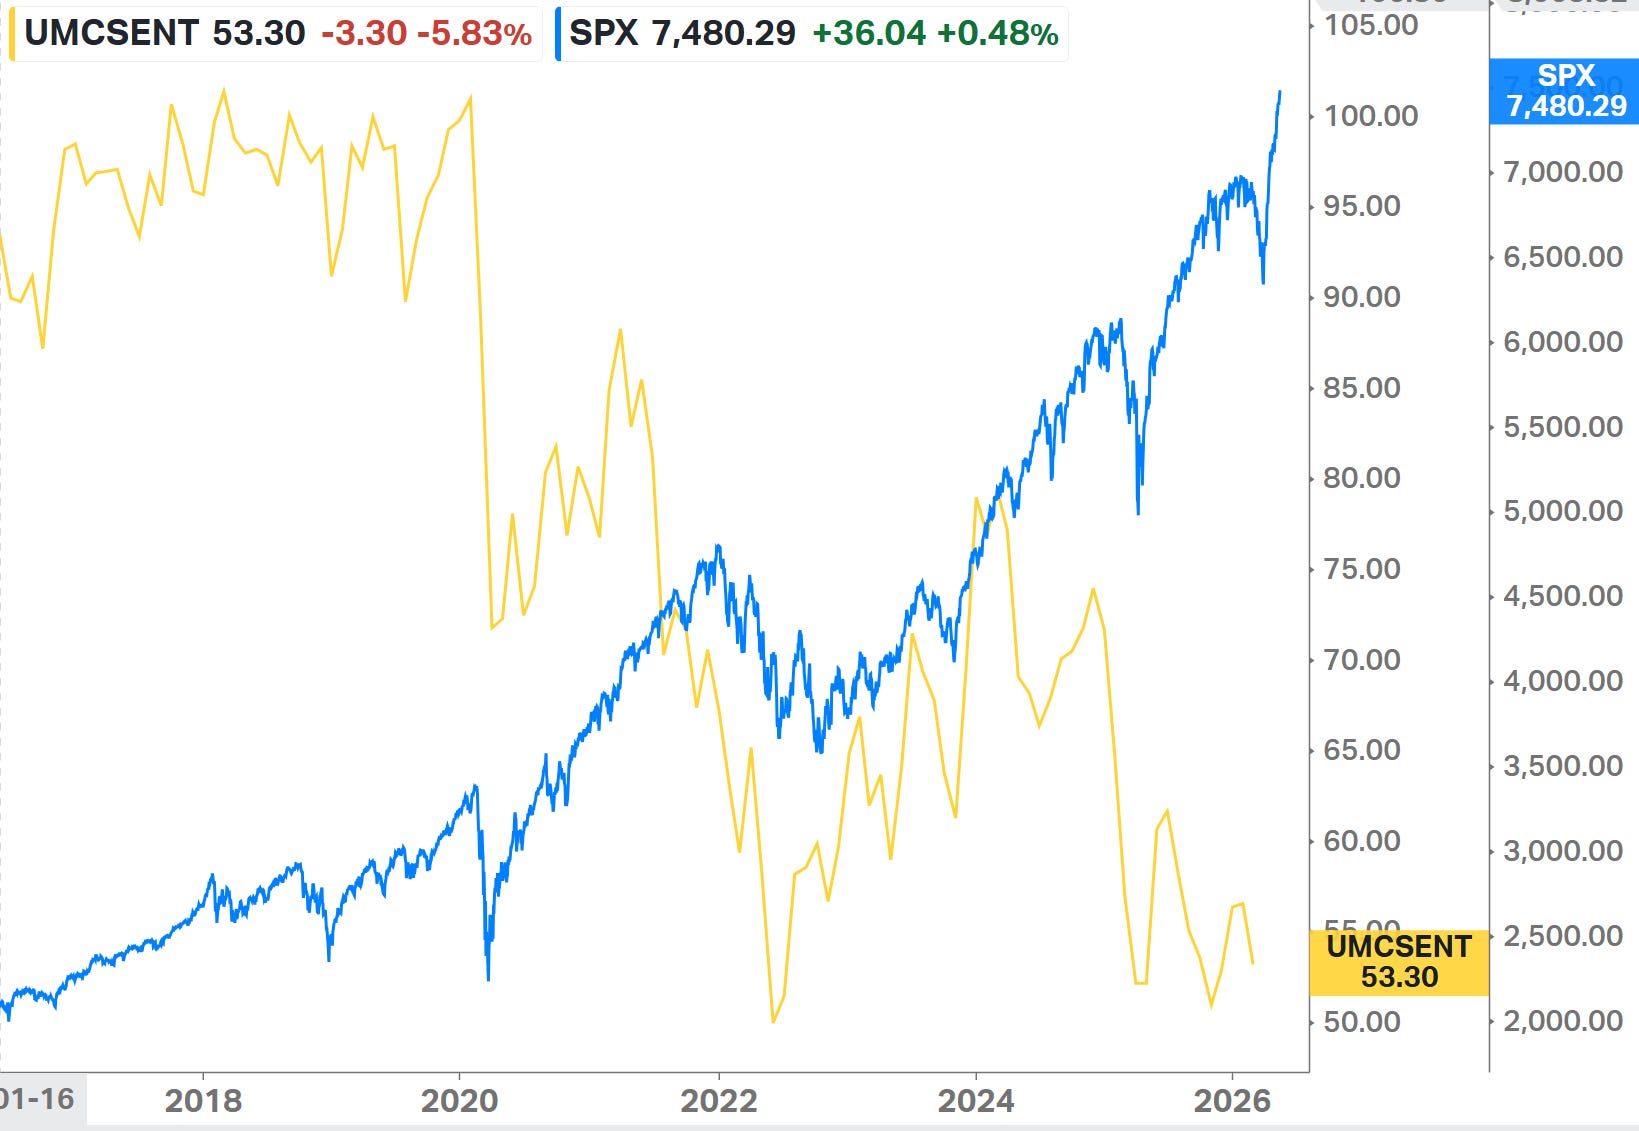
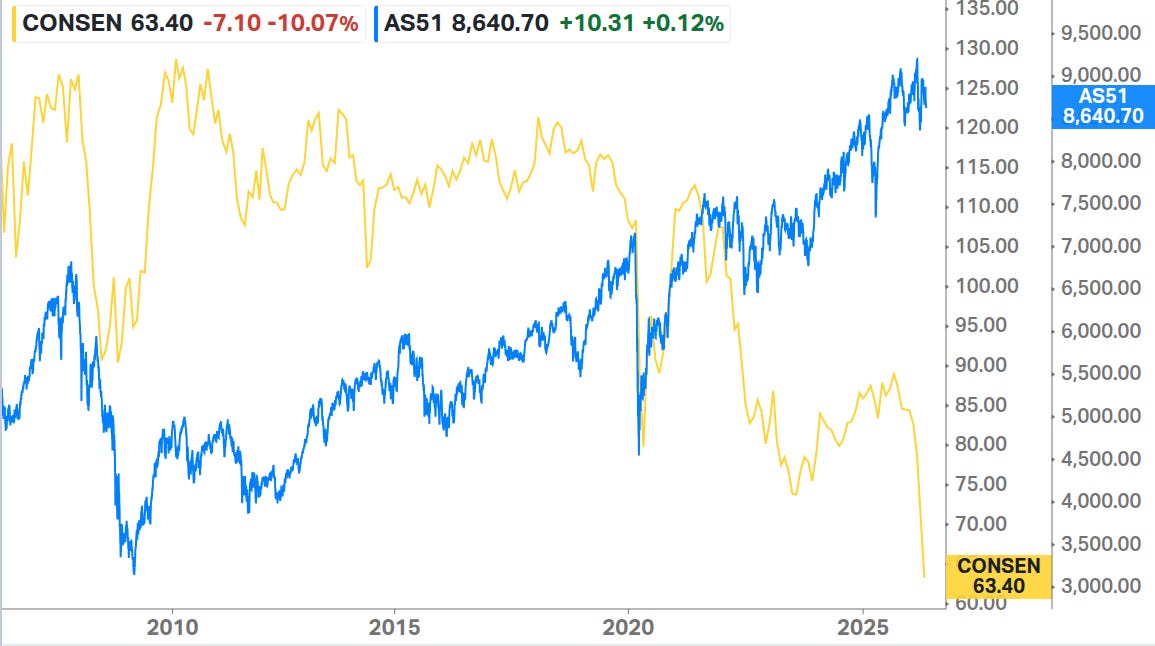
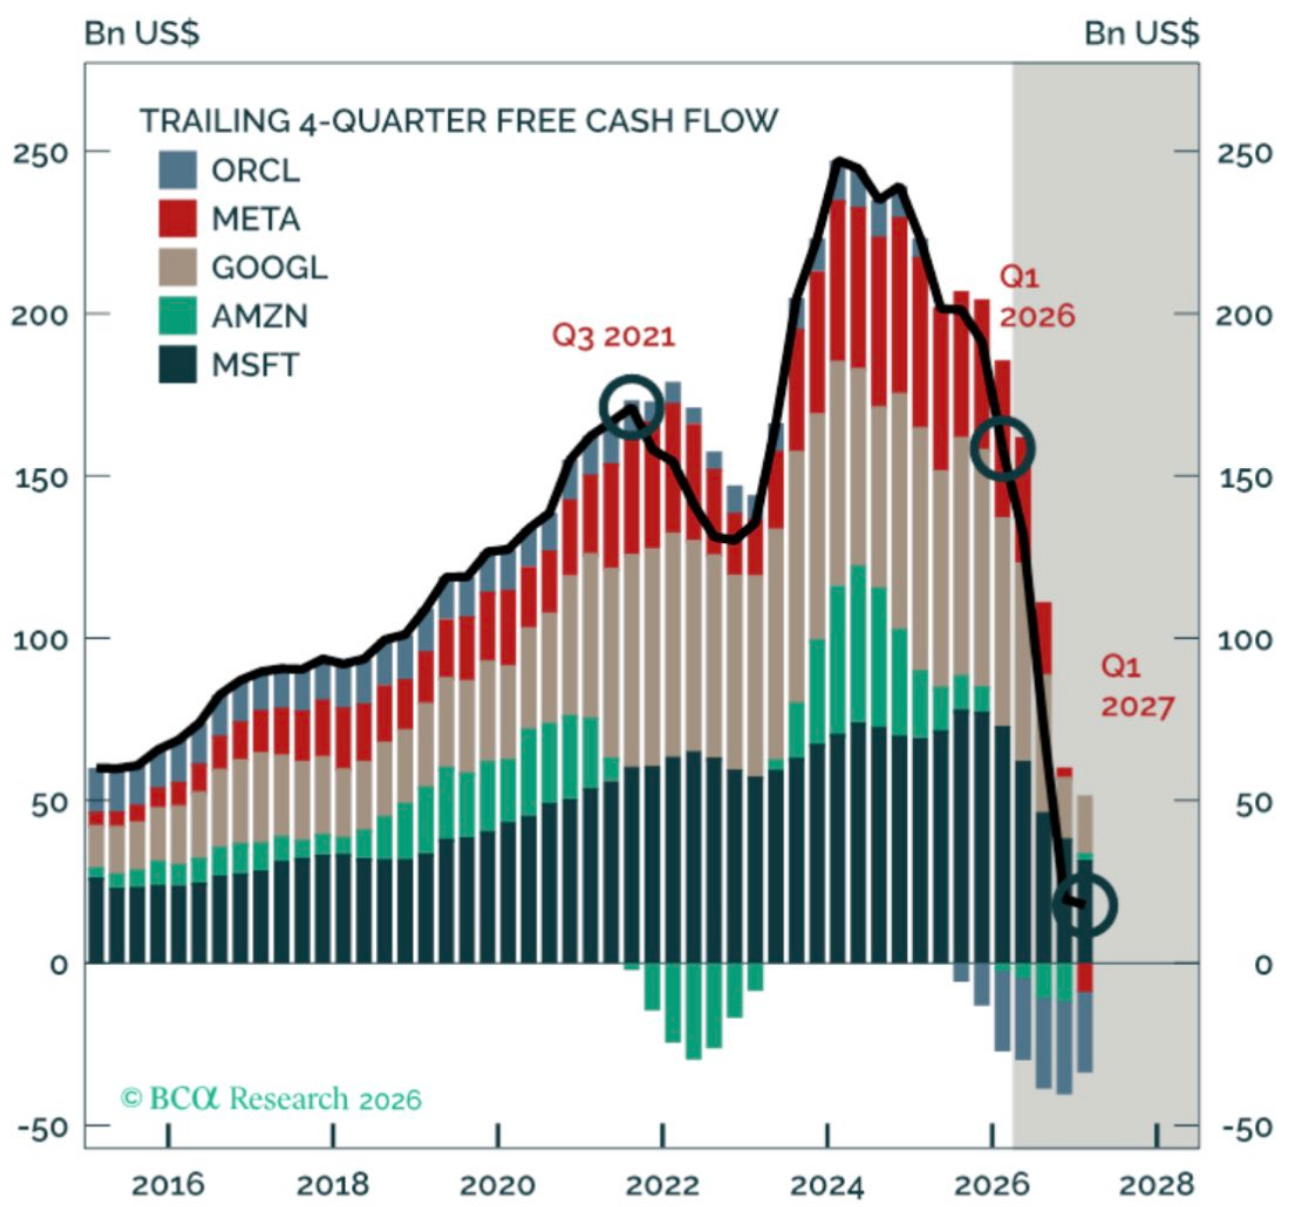
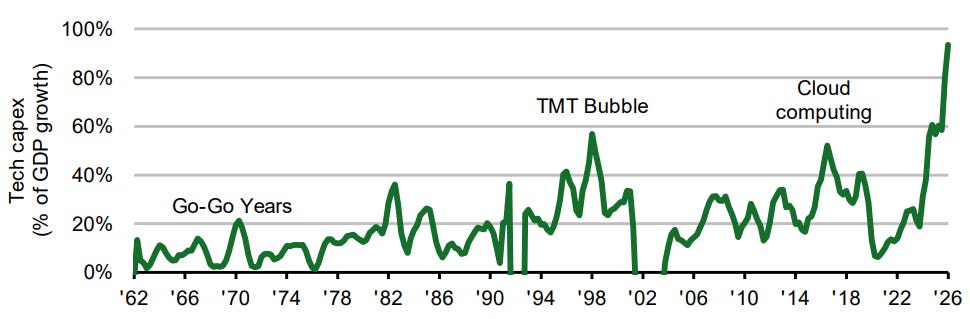
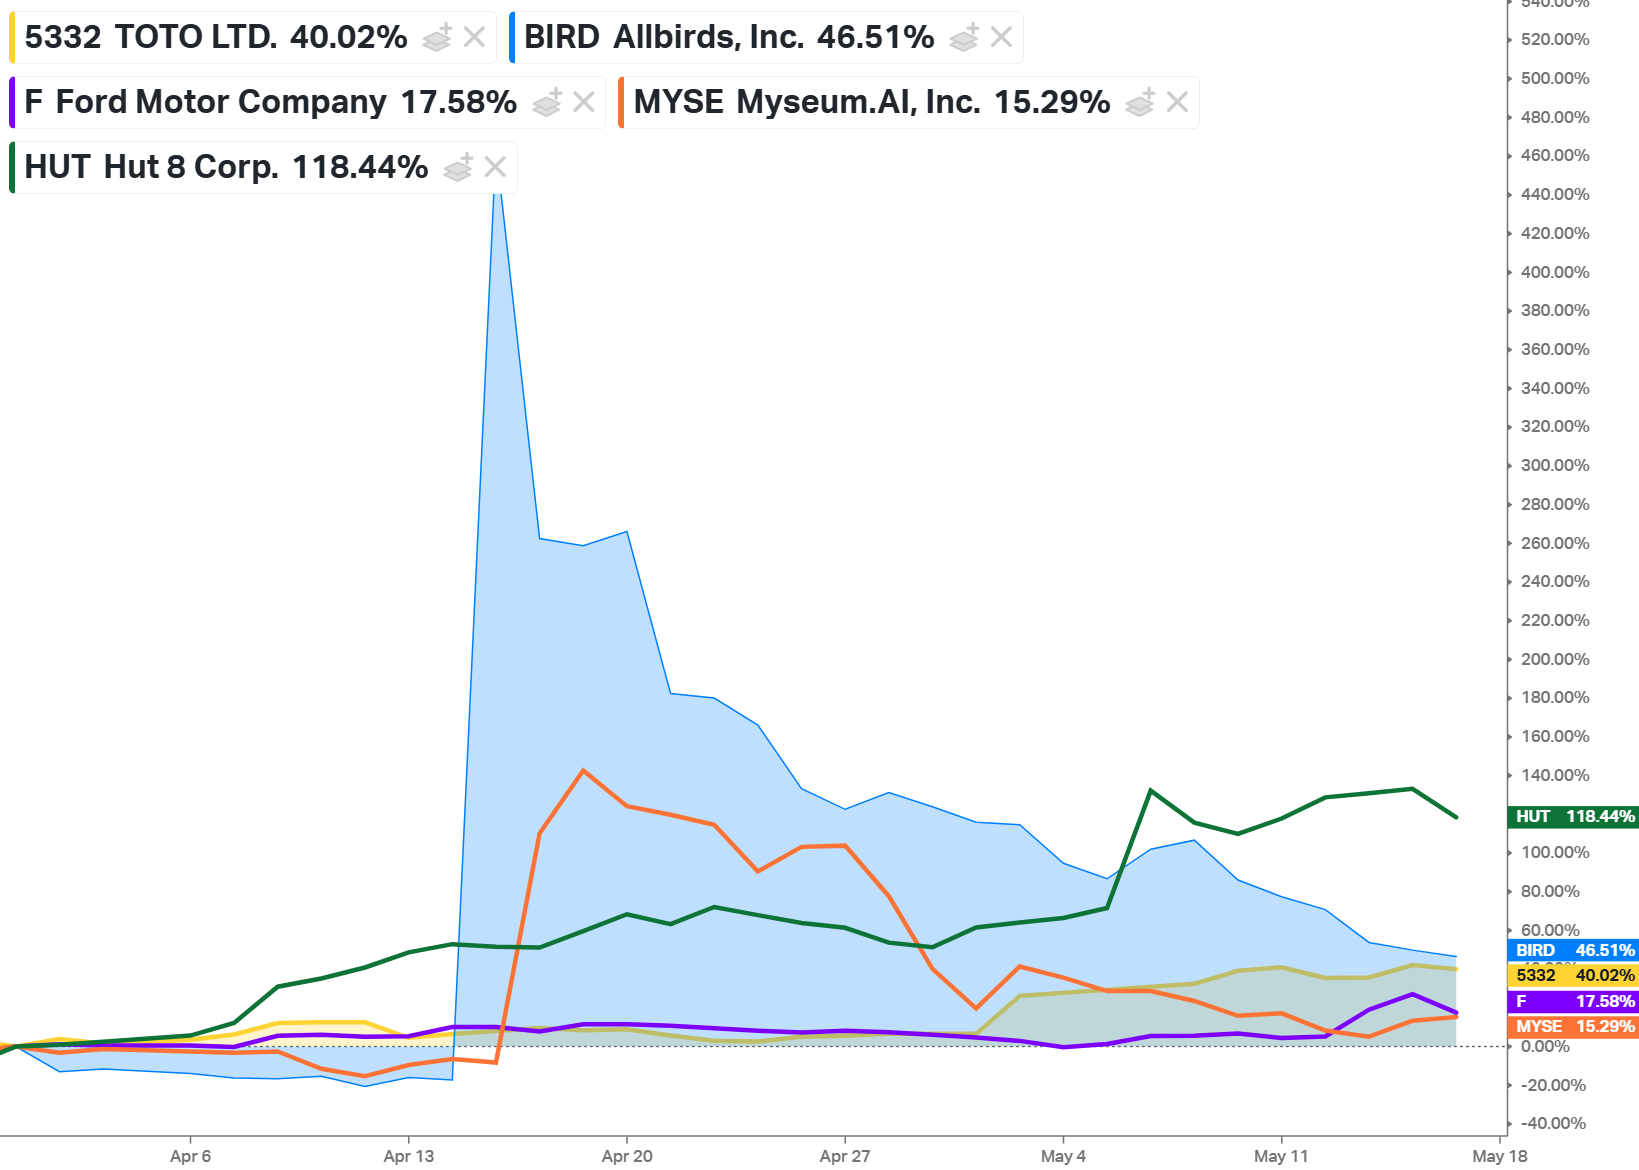
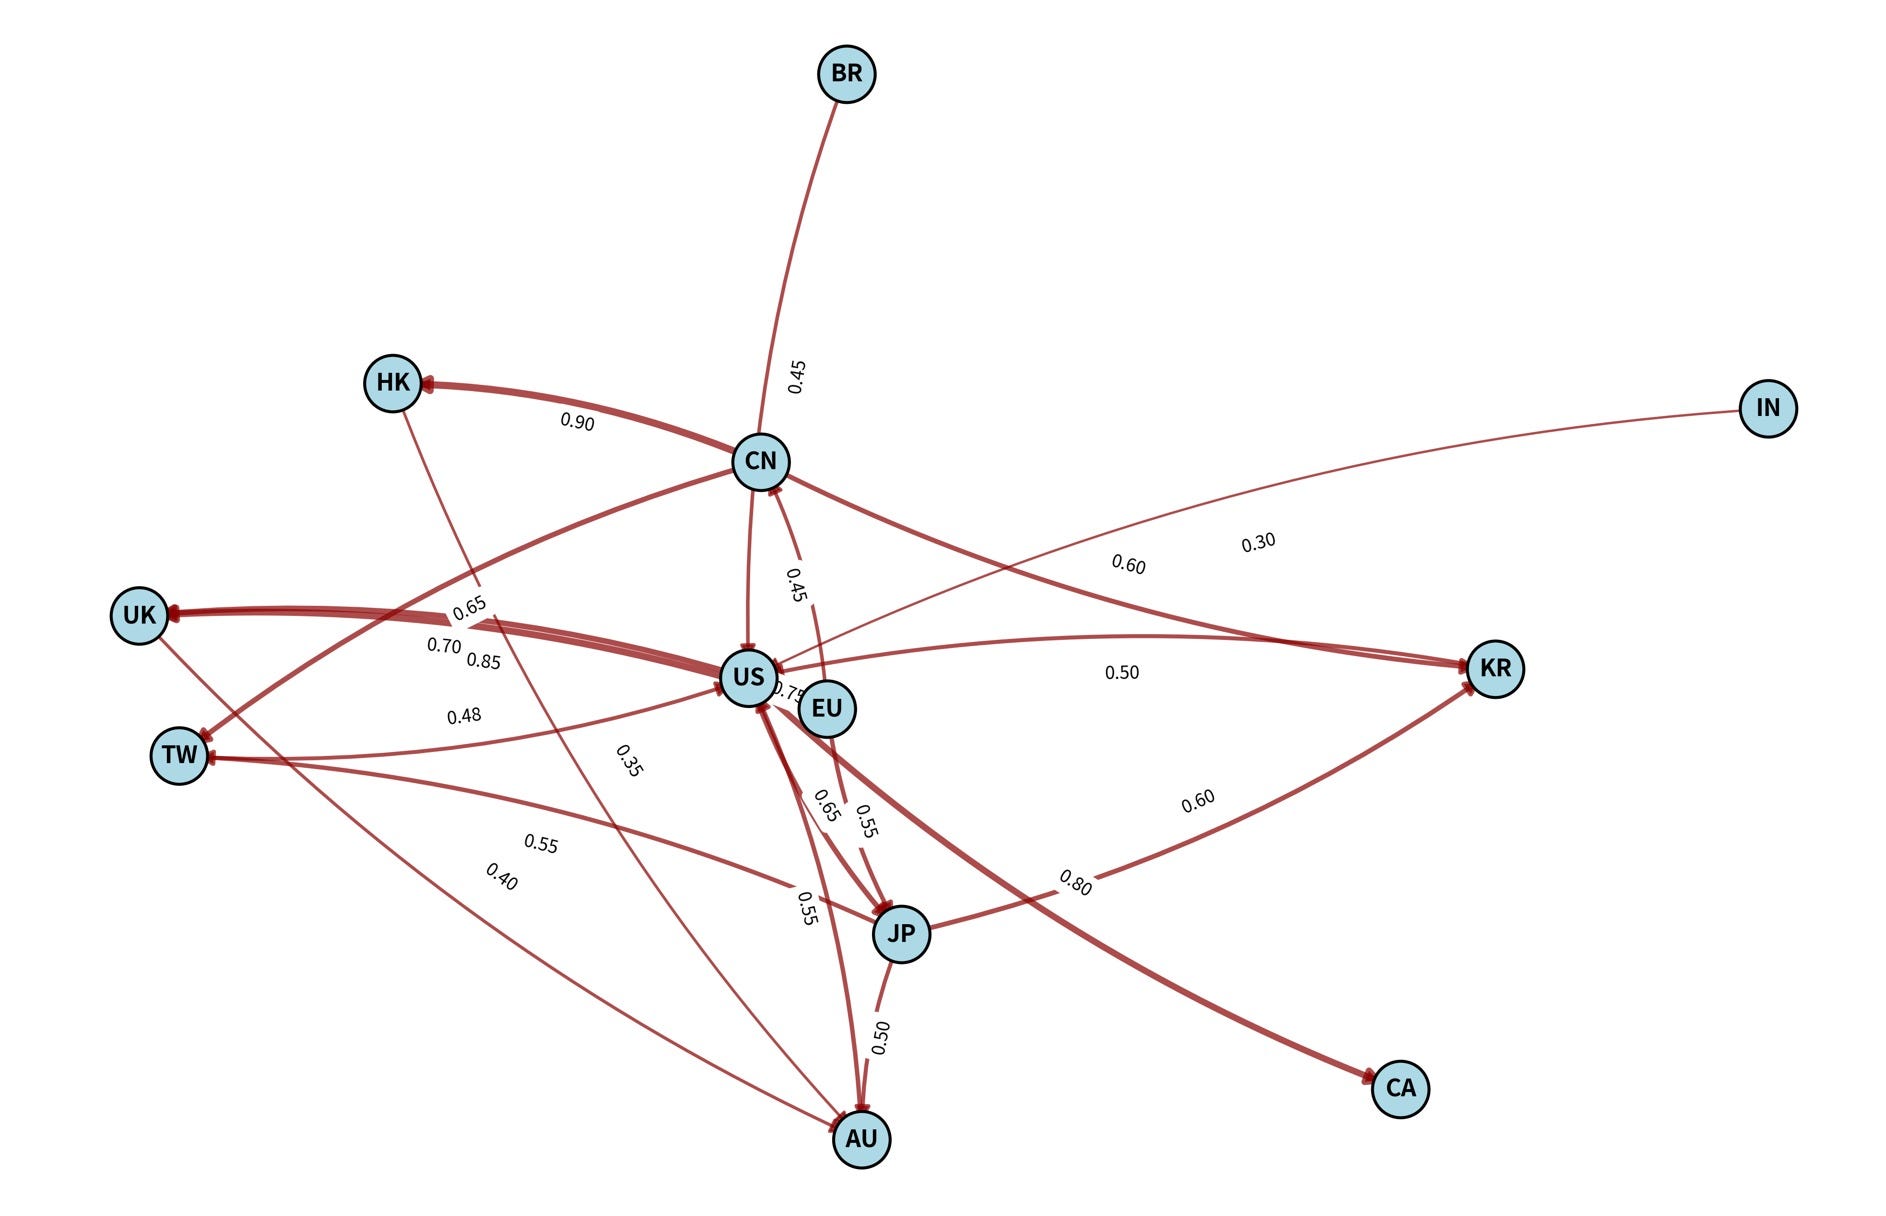
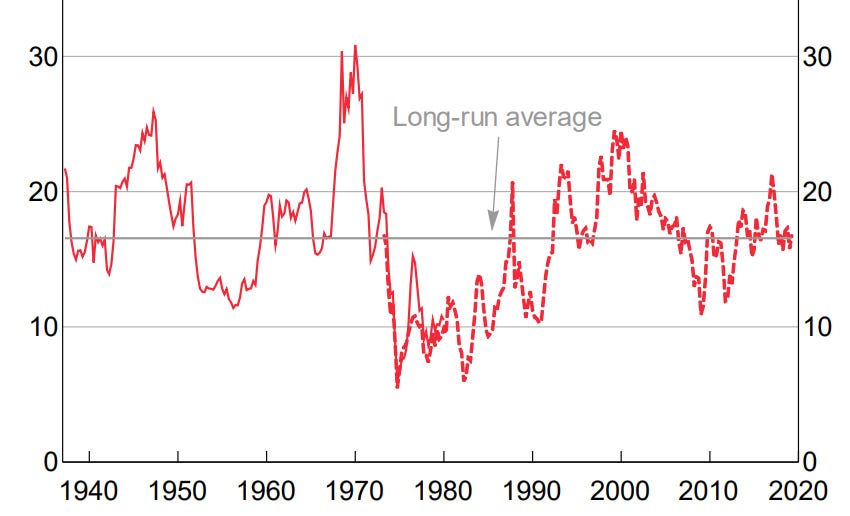
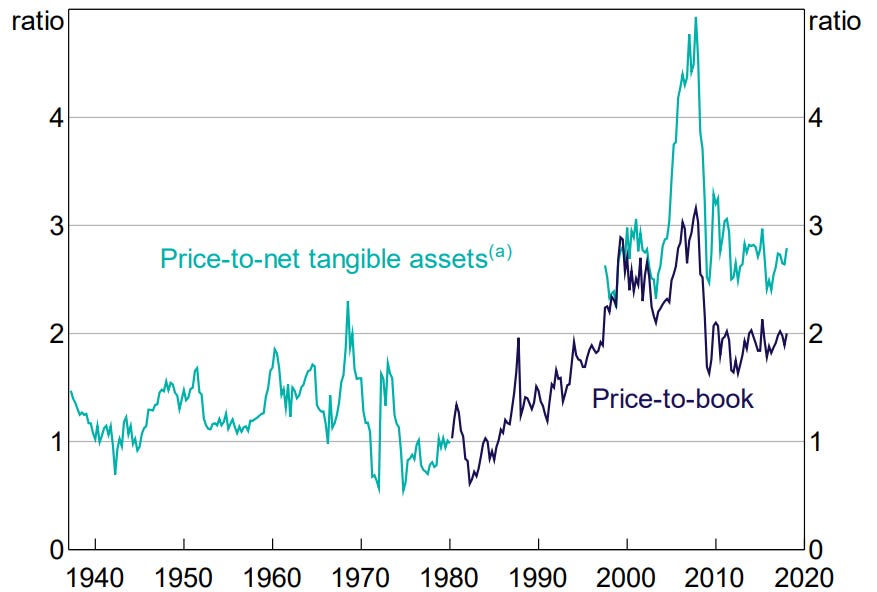
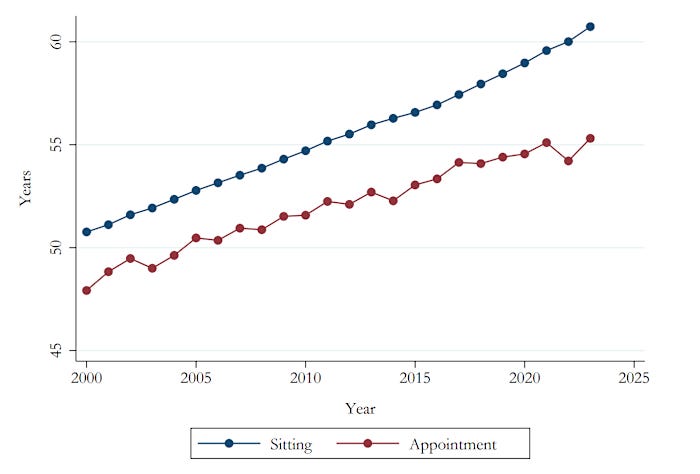
10k Words Equitable Investors May 2026 (2-minute read) The "Magnficient 7" continue to lead the charge with investors exhibiting a strong appetite for risk. But global oil inventories are tracking low and so is consumer sentiment in Australia and the US. And so is the free cash flow of those large tech companies as tech capex approaches 100% of US GDP. The game of pivoting to the hot space has fired up with a shoe maker and a range of others associating themselves with "AI" and receiving a share price bump. We map the interconnectedness of global equity markets - and look at the long-term shift away from asset bases in Australian valuations. Finally, CEOs are getting older! Magnificent 7 v the world
Source: Koyfin US risk appetite and equity momentum - hitting levels last seen in 2020
Source: Goldman Sachs Investment Research Global oil inventories
Source: JP Morgan Commodities Research US consumer sentiment v. equities
Source: Koyfin Australian consumer sentiment v equities
Source: Iress, Koyfin "Mega Tech" free cash flow diminished - "capital light" model gone
Source: BCA Research Tech capex approaching 100% of US GDP
Source: Panmure Liberum AI pivot or pump?
Source: Equitable Investors, Koyfin Global equity interconnectedness network (simulted via piecewise Network VAR Spillover Coefficients)
Source: Grok, Equitable Investors Australian equity market's long-term trailing valuation multiples
Source: RBA Average age of CEOs over time (US data)
Source: FT Alphaville, "Aging at the Very Top" Funds operated by this manager: Equitable Investors Dragonfly Fund Disclaimer Past performance is not a reliable indicator of future performance. Fund returns are quoted net of all fees, expenses and accrued performance fees. Delivery of this report to a recipient should not be relied on as a representation that there has been no change since the preparation date in the affairs or financial condition of the Fund or the Trustee; or that the information contained in this report remains accurate or complete at any time after the preparation date. Equitable Investors Pty Ltd (EI) does not guarantee or make any representation or warranty as to the accuracy or completeness of the information in this report. To the extent permitted by law, EI disclaims all liability that may otherwise arise due to any information in this report being inaccurate or information being omitted. This report does not take into account the particular investment objectives, financial situation and needs of potential investors. Before making a decision to invest in the Fund the recipient should obtain professional advice. This report does not purport to contain all the information that the recipient may require to evaluate a possible investment in the Fund. The recipient should conduct their own independent analysis of the Fund and refer to the current Information Memorandum, which is available from EI. |

21 May 2026 - Global Perspectives: Addressing the most essential questions around AI
|
Global Perspectives: Addressing the most essential questions around AI Janus Henderson Investors May 2026 (Duration: 29 minutes) In this episode, Portfolio Manager Denny Fish takes a deep dive into the current state of artificial intelligence (AI), including the latest advancements, its potential to propel economic growth, and the rise of agentic AI and its impact on software business models. He also shares insights from a recent research trip in China. |
|
Funds operated by this manager: Janus Henderson Australian Fixed Interest Fund , Janus Henderson Conservative Fixed Interest Fund , Janus Henderson Diversified Credit Fund , Janus Henderson Global Natural Resources Fund , Janus Henderson Tactical Income Fund , Janus Henderson Australian Fixed Interest Fund - Institutional , Janus Henderson Conservative Fixed Interest Fund - Institutional , Janus Henderson Cash Fund - Institutional , Janus Henderson Global Multi-Strategy Fund , Janus Henderson Global Sustainable Equity Fund , Janus Henderson Sustainable Credit Fund All opinions and estimates in this information are subject to change without notice and are the views of the author at the time of publication. Janus Henderson is not under any obligation to update this information to the extent that it is or becomes out of date or incorrect. The information herein shall not in any way constitute advice or an invitation to invest. It is solely for information purposes and subject to change without notice. This information does not purport to be a comprehensive statement or description of any markets or securities referred to within. Any references to individual securities do not constitute a securities recommendation. Past performance is not indicative of future performance. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested. Whilst Janus Henderson believe that the information is correct at the date of publication, no warranty or representation is given to this effect and no responsibility can be accepted by Janus Henderson to any end users for any action taken on the basis of this information. |

20 May 2026 - Who's winning the AI race - and does it matter?
|
Who's winning the AI race - and does it matter? abrdn May 2026 (Duration: 27 Mins) In this episode, we explore how artificial intelligence (AI) is reshaping global competition. We compare the US and China's approaches to AI, looking beyond the headlines to examine models, infrastructure, power, government strategy and the real world application of AI across economies. Nick speaks to Bob, and they discuss whether AI really represents a race between the US and China, how different policy and market structures are shaping outcomes, and why the implications for growth and productivity may matter more than who is technically "ahead" at any given moment. |
|
Funds operated by this manager: abrdn Sustainable Asian Opportunities Fund , abrdn Emerging Markets Equity Fund , abrdn Sustainable International Equities Fund , abrdn Global Corporate Bond Fund (Class A) |

reaching new highs during April. (2-minute read)
19 May 2026 - Glenmore Asset Management - Market Commentary
|
Market Commentary - April Glenmore Asset Management May 2026 (2-minute read) The US market appeared to shrug off the ongoing war in Iran, reaching new highs during April. This was primarily driven by the tech sector, resulting in the NASDAQ rising +15.3%, representing its strongest monthly gain since April 2020. Whilst not being as tech-heavy, the S&P 500 was boosted by similar factors, rising +10.4%. US markets easily outpaced their international peers, with the Euro Stoxx 50 and FTSE 100 rising +5.6% and +2.0% during the month, respectively. Similarly, domestic markets lagged the US, with the ASX All Ordinaries Accumulation Index rising +2.4%. The gains were led by the Tech (+12.3%) and Real Estate (+8.0%) sectors, whilst Healthcare was the key detractor (-8.4%), dragged down by Cochlear (COH), which fell -44% following an earnings downgrade. In bond markets, the US 10-year bond yield rose +5 basis points (bp) to 4.37%, whilst its Australian counterpart rose +9bp to 5.1%. The Australian dollar rebounded during the month, rising +4.3% to US$0.72, implying an increase of 3.0 cents. Funds operated by this manager: |

18 May 2026 - China's Luxury Reset: What we're seeing on the ground and why it matters

Datt Capital.
15 May 2026 - Manager Insights | Datt Capital
|
Chris Gosselin, CEO of FundMonitors.com, speaks with Emanuel Datt, founder and Chief Investment Officer at Datt Capital. Emanuel discussed recent market volatility, the divergence between large and small caps, and the opportunities emerging in the small companies space. He also discussed Datt Capital's approach to sector analysis, including technology, AI adoption, and energy, as well as the Fund's cash position and ability to act on market dislocations. Disclaimer: This conversation with FundMonitors was recorded prior to the release of the federal budget. |
|
|
Funds operated by this manager: Datt Capital Absolute Return Fund , Datt Capital Small Companies Fund |
|
|
|

14 May 2026 - It's the end of the world as we know it... and We Feel Fine.
|
It's the end of the world as we know it... and We Feel Fine. Revolution Asset Management April 2026 5-minute read |
|
Seeing the recent media headlines, one could be forgiven for thinking private credit is facing its end-of-the-world moment. The current media commentary has been dominated by rising default fears, valuation and redemption pressures, and warnings that the asset class is being tested for the first time in its modern form. The tone is urgent and unmistakably negative. This brings to mind the popular band, R.E.M.'s, 1987 release It's the End of the World as We Know It - a rapid fire sequence of alarming imagery that sounds like chaos unfolding in real time. However, as Michael Stipe (lead singer of R.E.M.) reminds us in the chorus... "I feel fine". The contrast reflects what Revolution Asset Management (Revolution) is experiencing in today's private credit market. While the noise and volatility are real and persistent, so too are disciplined deployment, conservative underwriting, a deliberate focus on non cyclical sectors, a refusal to chase yield (and risk), and experience driven portfolio construction which continues to underpin resilience. Why US Centric Developments Are Shaping Global Private Credit SentimentThere is no denying that parts of the global private credit market are under pressure. Much of the negative press is driven by developments in the U.S., where the asset class has grown rapidly over the past decade and where stress is now emerging in specific segments. This includes the so-called "SaaSpocalypse", redemption and liquidity pressures or rising default fears. In the U.S., private credit has had significant exposure to software and technology borrowers, alongside the widespread adoption of covenant lite structures that emerged during a prolonged period of strong inflows into the private credit segment. Additionally, general lending terms continued to weaken, and lenders were extending higher leverage, simultaneously. Over time, vulnerabilities that were already embedded in parts of the U.S. private credit market, such as higher opening leverage, aggressive EBITDA adjustments, covenant-lite structures and focusing on growth rather than cash flow generation were exposed, and some of those structures have now come under strain. Selective defaults, payment in kind interest, and amendments to loan terms have naturally attracted attention. As Mike Tyson once said: "Everybody has a plan until they get punched in the face". In the current environment, rapid deployment and relaxed processes work - until they don't. In this credit cycle, the consequences could be more severe, with recoveries potentially lower due to higher opening leverage and weaker underwriting standards. This narrative has been amplified by publicly traded vehicles. Share price volatility, widening discounts to net asset value, and a handful of high profile credit events have made for compelling headlines. But these headlines, by their nature, compress nuance and often extrapolate localised issues into broad conclusions about an entire asset class. The Reality: Dispersion, Not DeteriorationBeneath the surface, the private credit landscape is showing dispersion rather than systemic weakness. Performance outcomes are diverging based on underwriting standards, sector exposures, portfolio construction, and manager experience. Portfolios built with aggressive leverage assumptions, heavy exposure to smaller companies and cyclical earnings, or generally poor underwriting standards are more exposed to investor sentiment and market ructions. By contrast, private lenders that prioritised downside protection, with conservative structures, and focused on borrower cash flow stability are experiencing more stable outcomes. This is not unusual. Credit cycles have always been periods where discipline is revealed and rewarded. What about the "SaaSpocalypse"?SaaS (Software as a Service) companies that were previously considered market darlings, have also come under pressure as investors fear the potential impacts of AI disrupting traditional SaaS business models. For context, U.S. private credit portfolios and Business Development Companies typically contain quite material software and technology exposures (generally in the order of 20-30%). This compares to the single-digit-percentage of the Australian private credit market being in the software segment, with literally a handful of names, which are commonly referred to as "mission critical". Additionally, the concept of Annual Recurring Revenue, while foreign in Australia, is commonplace in the U.S., where private lenders provide funding based not on EBITDA and cash flow, but how fast their revenue is growing. As was recently outlined in the article: AI, Software, and Private Credit: Separating Credit Risk from Market Noise , not all software companies are created equally. This emphasised that the more well-known Australian mission-critical software providers have significant moats around their business in terms of the degree of embeddedness in their customer operations as well as already incorporating AI within their platforms to enhance their offering. Additionally, the Australian software companies in the private credit space are also considered platforms rather than applications, further adding to their embedded and more defensive nature. Set against Australia's more conservative lending framework and historically strong equity buffers, this means that while enterprise values may be lower than they were even a few months ago, a substantial layer of equity protection remains in place for senior lenders. In this structure, equity absorbs valuation pressure first, with credit impacts only emerging after a significant erosion of equity value. Why Private Credit Looks Different in Australia and New ZealandImportantly, Australia does not map neatly into the U.S. private credit narrative. Australian private credit has developed along a very different path, shaped by market structure, regulation, and borrower behaviour, with Australian private credit focusing more on conservative structures, asset backed strategies, and businesses with tangible cash flows.
For these reasons, applying U.S centric conclusions to Australian portfolios risks missing what matters on the ground. Stability through volatility, not dependent on optimismAgainst this backdrop, Revolution's portfolio positioning has been deliberate. Capital deployment has consistently prioritised credit discipline, with a focus on structure, security and borrower quality. Revolution has concentrated on non cyclical industries with stable demand drivers and resilient cash flows, diversified across the Australian and New Zealand private credit landscape, allowing the investment team to be selective and find the best relative value in markets they know well. Patient capital has also been a defining advantage through this period of volatility. By structuring funds with long�'dated capital and conservative liquidity settings, Revolution does not become a forced seller when markets dislocate. Instead, Revolution acts deliberately at moments when others cannot. As market volatility has increased, pockets of the private credit market have experienced liquidity�'driven selling, particularly from vehicles managing redemptions or facing near�'term funding constraints. These situations are rarely driven by a deterioration in underlying asset quality, but by the need to raise liquidity. For private credit managers with patient capital, this creates opportunity. The ability to acquire high�'quality loans, often at discounts, creates opportunities to deploy capital at more compelling risk�'adjusted returns. This dynamic reinforces why stability through volatility matters, not just defensively, but as a source of long�'term return generation. Revolution has encountered cycles like this before. Periods of rising interest rates, tightening liquidity, and heightened scrutiny are not new. What changes from cycle to cycle is who is prepared for them. Rather than viewing volatility as a signal to retreat, Revolution sees this as a natural phase of the credit cycle, one that reinforces the value of conservative underwriting, patience, and manager experience. Amid the market noise, discipline and resilience prevailsWhen R.E.M. sang It's the End of the World as We Know It, they weren't singing about ignoring risk or pretending chaos does not exist. It is about perspective. Amid the noise, there is a calm recognition that not everything unfolding is unexpected and not everything is catastrophic. The private credit landscape today is undergoing a healthy process of differentiation. Strong portfolios are distinguishing themselves from weaker ones. Structural discipline will be rewarded. And markets are once again reminding participants that credit is, ultimately, about risk management rather than return maximisation. While headlines may stay dramatic and volatility may persist, private credit lenders with resilient portfolios especially in markets like Australia and New Zealand, with materially different fundamentals to the U.S., remain well positioned. The world may sound like it is ending, but from where we sit, we feel fine. |
|
Funds operated by this manager: Revolution Private Debt Fund II , Revolution Wholesale Private Debt Fund II - Class B Important Information This information is for wholesale and professional investors only and has been prepared by Revolution Asset Management Pty Ltd ACN 623 140 607 AFSL 507353 ('Revolution'). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 ('CIML') is the trustee and issuer of units for the Revolution Private Debt Fund II, Revolution Wholesale Private Debt Fund II (collectively 'the Funds'). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 ('Channel') provides investment infrastructure and distribution services for Revolution and is the holding company of CIML. FundRock NZ Limited is the issuer of units in the Revolution Private Debt PIE Fund (NZD) (the 'NZ Fund'). Public Trust is the independent trustee of the Scheme of the NZ Fund. Revolution is the appointed Investment Manager for the NZ Fund. Refer to fundrock.com/fundrock-new-zealand for more information. The NZ Fund is intended for the exclusive use of wholesale investors, as defined by the Financial Markets Conduct Act 2013. This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party ('Recipient'). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). Revolution is not licensed in Australia to provide financial product advice or other financial services to retail investors. The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice. Neither Revolution, Channel, CIML, FundRock NZ Limited or their representatives and respective employees or officers (collectively, 'the Beneficiaries') make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance. For further information and before investing, please read the Information Memorandum available on request. |
