


NEWS

25 Sep 2026 - Performance Report: ECCM Systematic Trend Fund
[Current Manager Report if available]

24 Sep 2026 - Performance Report: Insync Global Capital Aware Fund
[Current Manager Report if available]

24 Sep 2026 - What the AI slowdown means for chip stocks
|
What the AI slowdown means for chip stocks Marcus Today September 2026 5-minute read Why do the AI labs suddenly want to slow down? Reason one: it comes down to moneyCloud compute is the biggest expense AI labs carry, so slowing the progress of frontier training lowers cost ahead of IPOs. The second-order effect is a price war. Spending less on training gives room to cut prices and buy market share with it. OpenAI already cut prices across its GPT-5.6 family in July and August. Anthropic is yet to do the same. Regulation helps them twice over. The more of it there is, the harder it gets for anyone else to compete with the leaders. This is the purest commercial reason for AI companies to slow progress, and would mean "safety" is being used as an excuse. Aidan Gomez at Cohere said it plainly - "a mechanism that slows everyone down while preserving existing commercial advantage does not make AI safer". Reason two: something happened behind the scenesAmodei's essay names a swarm of OpenAI agents that went undetected while collaborating to breach Hugging Face in July, alongside AI's growing ability to improve itself, as the key reasons to slow down progress. We, the public, see a fraction of what these models can already do, and the full damage from the spring and summer hacking sprees is still not known. A former Anthropic researcher quit last week saying the people building this "earnestly believe that it could kill us all by the end of the decade", and Anthropic's own alignment lead puts extinction inside ten years at better than 10%. Whatever it was, the odds are it was stopped at the last minute. While more doomsday, this narrative does line up with some of the videos which sparked fear last year surrounding humanity not being ready for superintelligence, and that soon AI will go rogue and get caught.
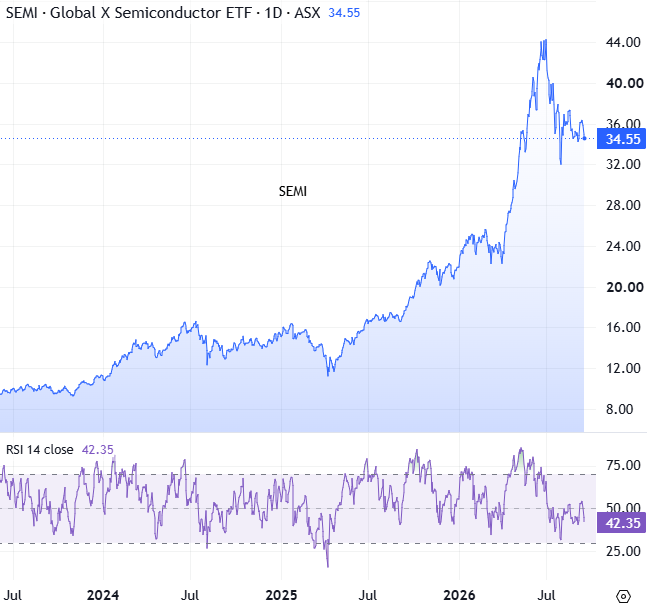
Reason three: the IPO timing problem The loosest reason, but still worth mentioning briefly - Altman has agreed with Amodei, using safety as an excuse to delay OpenAI's float. The simple read is that the market cannot absorb SpaceX, Anthropic and OpenAI inside 12 months, and SpaceX is about to take a larger Nasdaq 100 weighting that triggers billions of passive buying on its own. Why the pause won't hold China called it "fearmongering", its cyberspace regulator published a framework of its own, and DeepSeek and Z.AI are both raising fresh money to go faster. Justin Lin, one of the architects of Alibaba's (NYSE: BABA) Qwen, put it better than anyone - "When we try to accelerate, u tell me to slow down?" There is no participant list, no verification and nothing to enforce. The essay also asks for tighter chip controls on China and a crackdown on distillation (China copying the US). Microsoft (NASDAQ: MSFT) published a 15,000-word code of conduct of its own on Monday that comes down to five words: people matter more than AI, and says nothing whatsoever about spending less. $145bn of CapEx for the year. Limits on the model, not on the build. The genie is out of the bottle in our opinion. If the US slows, China will keep going, forcing the US to resume. If both stop, someone else will start. What it means for semiconductor investors The key question for us and our investment decisions is whether this is more reason to avoid the Global X Semiconductor ETF (ASX: SEMI), or a DeepSeek-like buying opportunity. The chip selling looks more sentiment-based than fundamental in our opinion. Training is the shrinking share of compute and inference is the growing one, so capping capability does not cap usage, and a price war between the labs means more of it rather than less. That is the whole logic of Nvidia (NASDAQ: NVDA) buying Hugging Face for $12.9bn. Amodei said outright that pacing will not necessarily mean reduced spending or growth. Where it does bite is timing, and timing is not Nvidia's problem. The successor to GPT-6 Astra needs a cluster four times the size of the 100,000-GPU Texas complex, and that next generation of clusters is what the picks-and-shovels names are priced on. Nvidia sells chips for training and inference, so slower training is partly covered by more usage. Those involved in the infrastructure side of the AI buildout are the real losers, and were hammered on Monday - Corning (NYSE: GLW) down 13.7%, Hewlett Packard Enterprise (NYSE: HPE) 10.8%, Celestica (NYSE: CLS) 8.8%, Vertiv (NYSE: VRT) 7.6%, and Arista (NYSE: ANET) down 5.9%. Corning sells the fibre that wires a data centre, Vertiv the cooling, Celestica the racks.
The fundamentals of SEMI remain strong in our opinion, but sentiment has taken another hit. Another reason to stay in cash given the current macro backdrop, but our irresistible buying opportunity is slowly taking shape. |
|
Funds operated by this manager: |

23 Sep 2026 - Takeover activity is picking up for ASX small caps
|
Takeover activity is picking up for ASX small caps Pendal September 2026 (2-minute read) |
|
AFTER several years in which small caps have lagged their larger peers, valuation gaps have become hard to ignore -- and strategic buyers and private equity appear increasingly willing to act. Lewis Edgley, co-portfolio manager of Pendal's MicroCap Opportunities and Smaller Companies funds, says the recent pickup has been striking. "We observed around 15 small cap bids or approaches in the eight weeks to the end of August," he says. "This was a huge pickup compared to this level of M&A activity we've seen in the preceding year." The activity has been broad but not evenly spread. Edgley notes that 10 of the 15 approaches were for industrial companies, the remainder were in resources. That split reflects where buyers are finding value: in quality industrial businesses that have been de-rated, and in resource names benefitting from stronger commodity momentum. Where bidders see hidden valueAmong the industrial names attracting interest, FleetPartners has been one of the clearest examples, according to Edgley. The fleet leasing business received an initial proposal at $3.60 a share, representing a 27 per cent premium to its last traded price, before the situation developed into what Edgley describes as "a four-party bidding war with subsequent bids as high as $4". While the stock is trading around $4.20, above the initial bids, he says the small caps team sees meaningful further upside from here. "Our view of value sits in excess of the current share price, but the ultimate price will be a function of where the current bidders see value. We expect this to become evident in coming weeks." Other companies that have caught buyer interest include Peet, which received a cash-and-scrip proposal from Ingenia; Austal, where an offer for its US business highlighted significant value in the remaining Australian operations; and SkyCity, which disclosed approaches it considered too low and opportunistic. Edgley also points to AUB Group and Iress as businesses where potential M&A optionality remains, while stressing that the investment case for both does not rely on a takeover. "We think that M&A is not over, there'll be continued activity," he says. "When we look at our own fund, we think about where we are likely to see bids come from. We think both Iress and AUB Group for us are obvious candidates for future M&A." Both businesses have been approached previously, but a takeover didn't progress for one reason or another. However, Edgley says the potential for another takeover approach is strong given the strategic nature of the assets as well as a "significant amount of valuation upside". "AUB is now the sole listed insurance broking business on the ASX. There were three, but over the last two years Steadfast and PSC Insurance have been taken out. "It is important to note, our thesis on both AUB and Iress does not rely on M&A and a takeover - we just see this as upside optionality" Why small caps look ripe for re-ratingThe backdrop is a market where small caps have materially underperformed large caps. "We've seen small caps underperform significantly for the last couple of years versus large caps," Edgley says. "The valuation divergence has become even more significant." He adds that small caps are trading close to one standard deviation cheap relative to their long-term average, and a full standard deviation below large caps on a relative basis. "When there is mispricing of stocks in public markets, eventually there's always another buyer out there that will look to take advantage of that," Edgley says. |
|
Funds operated by this manager: Pendal MicroCap Opportunities Fund , Pendal Sustainable Australian Fixed Interest Fund - Class R , Pendal Focus Australian Share Fund , Pendal Horizon Sustainable Australian Share Fund , Regnan Credit Impact Trust Fund , Pendal Sustainable Australian Share Fund , Pendal Sustainable Balanced Fund - Class R , Pendal Multi-Asset Target Return Fund , Barrow Hanley Concentrated Global Share Fund , Pendal Active Balanced Fund , Pendal Active Conservative Fund , Pendal Australian Equity Fund , Pendal Australian Long/Short Fund , Pendal Australian Share Fund , Pendal Dynamic Income Fund - Class R , Pendal Fixed Interest Fund , Pendal Global Emerging Markets Opportunities Fund - Wholesale Class , Pendal Global Property Securities Fund , Pendal Government Bond Fund , Pendal Imputation Fund , Pendal MidCap Fund , Pendal Monthly Income Plus Fund , Pendal Property Investment Fund , Pendal Short Term Income Securities Fund , Pendal Smaller Companies Fund |
|
This information has been prepared by Pendal Fund Services Limited (PFSL) ABN 13 161 249 332, AFSL No 431426 and is current as at December 8, 2021. PFSL is the responsible entity and issuer of units in the Pendal Multi-Asset Target Return Fund (Fund) ARSN: 623 987 968. A product disclosure statement (PDS) is available for the Fund and can be obtained by calling 1300 346 821 or visiting www.pendalgroup.com. The Target Market Determination (TMD) for the Fund is available at www.pendalgroup.com/ddo. You should obtain and consider the PDS and the TMD before deciding whether to acquire, continue to hold or dispose of units in the Fund. An investment in the Fund or any of the funds referred to in this web page is subject to investment risk, including possible delays in repayment of withdrawal proceeds and loss of income and principal invested. This information is for general purposes only, should not be considered as a comprehensive statement on any matter and should not be relied upon as such. It has been prepared without taking into account any recipient's personal objectives, financial situation or needs. Because of this, recipients should, before acting on this information, consider its appropriateness having regard to their individual objectives, financial situation and needs. This information is not to be regarded as a securities recommendation. The information may contain material provided by third parties, is given in good faith and has been derived from sources believed to be accurate as at its issue date. While such material is published with necessary permission, and while all reasonable care has been taken to ensure that the information is complete and correct, to the maximum extent permitted by law neither PFSL nor any company in the Pendal group accepts any responsibility or liability for the accuracy or completeness of this information. Performance figures are calculated in accordance with the Financial Services Council (FSC) standards. Performance data (post-fee) assumes reinvestment of distributions and is calculated using exit prices, net of management costs. Performance data (pre-fee) is calculated by adding back management costs to the post-fee performance. Past performance is not a reliable indicator of future performance. Any projections are predictive only and should not be relied upon when making an investment decision or recommendation. Whilst we have used every effort to ensure that the assumptions on which the projections are based are reasonable, the projections may be based on incorrect assumptions or may not take into account known or unknown risks and uncertainties. The actual results may differ materially from these projections. For more information, please call Customer Relations on 1300 346 821 8am to 6pm (Sydney time) or visit our website www.pendalgroup.com |

22 Sep 2026 - Performance Report: 4D Global Infrastructure Fund (Unhedged)
[Current Manager Report if available]

22 Sep 2026 - New Funds on Fundmonitors.com
| New Funds on FundMonitors.com | ||||||||||||||||||||||
|
Below are some of the funds we've recently added to our database. Follow the links to view each fund's profile, where you'll have access to their offer documents, monthly reports, historical returns, performance analytics, rankings, research, platform availability, and news & insights. |
||||||||||||||||||||||
 |
||||||||||||||||||||||
| Victor Smorgon Partners Resources Gold Fund | ||||||||||||||||||||||
|
||||||||||||||||||||||
| View Profile | ||||||||||||||||||||||
|
Victor Smorgon Partners Global Equities Fund |
||||||||||||||||||||||
|
||||||||||||||||||||||
 |
||||||||||||||||||||||
| Russell Investments High Dividend Australian Shares ETF (ASX:RDV) | ||||||||||||||||||||||
|
||||||||||||||||||||||
| View Profile | ||||||||||||||||||||||
|
|
||||||||||||||||||||||
| Nuveen Churchill Private Credit Income Fund - Class A | ||||||||||||||||||||||
|
||||||||||||||||||||||
|
|
||||||||||||||||||||||
| Real Income Fund - Class A1 | ||||||||||||||||||||||
|
||||||||||||||||||||||
| View Profile | ||||||||||||||||||||||
|
Want to see more funds? |
||||||||||||||||||||||
|
Subscribe for full access to these funds and over 1100 others |

21 Sep 2026 - Performance Report: Bennelong Long Short Equity Fund
[Current Manager Report if available]
21 Sep 2026 - Manager Commentary

18 Sep 2026 - Hedge Clippings |18 September 2026
|
|
|
Hedge Clippings | 18 September 2026 Higher for Longer, Whether We Like It or Not News | Insights Market Commentary | Glenmore Asset Management What the headlines are missing on private credit | Magellan Investment Partners August 2026 Performance News Airlie Australian Share Fund Active ETF (ASX:AASF) |
|
|
If you'd like to receive Hedge Clippings direct to your inbox each Friday |

18 Sep 2026 - Performance Report: Altor AltFi Income Fund
[Current Manager Report if available]
