NEWS

(5-minute read)
2 Sep 2026 - Why Warren Buffett waits for the fat pitch
|
Why Warren Buffett waits for the fat pitch Marcus Today August 2026 5-minute read Warren Buffett borrowed the fat pitch idea from a baseball legend, and it might be the simplest investing lesson there is. The origins of the fat pitchThe original idea of the Fat Pitch approach came from Ted Williams, a Boston Red Sox hitter, in his 1970 book The Science of Hitting. Williams carved the strike zone into seventy-seven squares, each the size of a baseball, and worked out his batting average for each one. In his best squares he hit around .400. In the low outside corner he hit around .230. His discipline was simple - only swing at balls in the good squares, and let the rest go by even if that meant taking strikes.
Why investors have it easier than battersBuffett took this and pointed out the bit that makes it better for investors than for batters. In baseball, you get called out on three strikes. In investing, there are no strikes. Nobody forces you to swing. You can stand there with the bat on your shoulder for months or years while thousands of pitches go past, and the only penalty is that nothing happens. So you wait for the fat pitch - the one that is slow, in the middle, and obviously mispriced - and then you swing hard and big. Swinging big is an important element - if you are going to ignore a lot of possible opportunities, then the easy ones you have to hit a lot harder. What this means for investorsWhat it means for an investor.
The punch card variantCharlie Munger said the trick is not being smarter than everyone else; it is being able to sit on your backside and do nothing for very long stretches without getting bored. Buffett added the Punch Card variant - he said, imagine you get a card with twenty punches on it for your whole investing life, one punch per decision, and when it runs out you are done. He reckoned you would make much better decisions and end up much richer. |
|
Funds operated by this manager: |

1 Sep 2026 - Australian Secure Capital Fund - Property Update
|
Australian Secure Capital Fund - Property Update Australian Secure Capital Fund August 2026 (1-minute read)
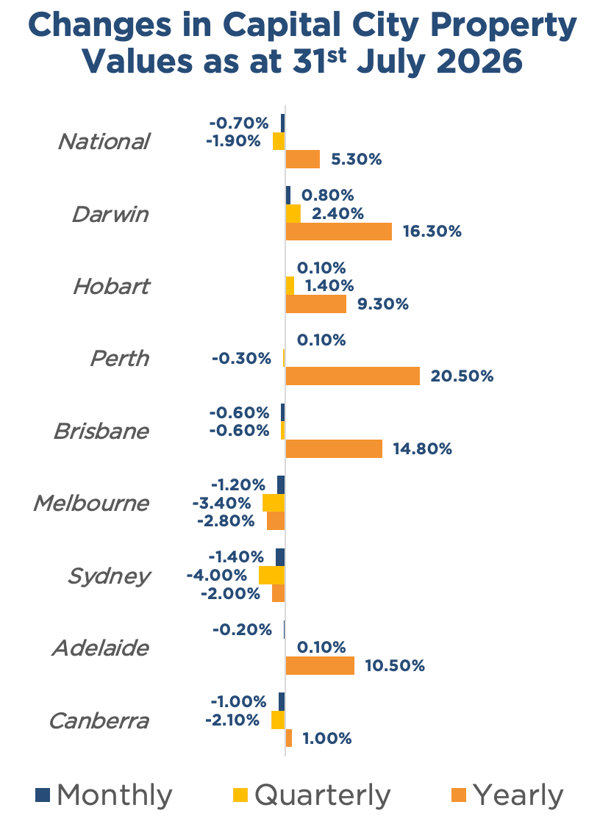
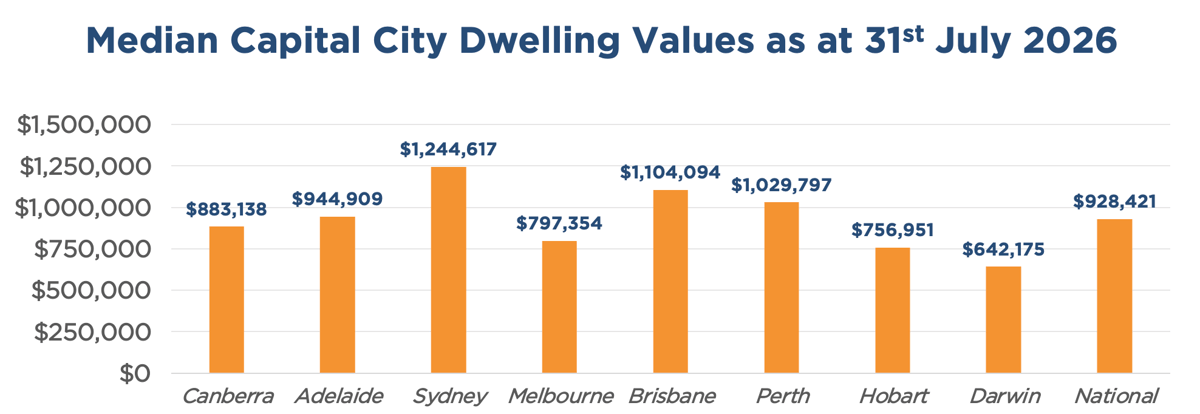
July continued the recent trend of declining Australian property values with a -0.7% monthly decrease. This marks the third consecutive monthly decline, and the largest single-month decline in Australian property values since December 2022. Sydney (-1.4%) and Melbourne (-1.2%) still lead the way in this regard, posting their sixth consecutive monthly declines. Even the mid-sized capitals of Perth (-0.3%), Adelaide (-0.2%), and Brisbane (-0.6%), which had previously been resilient in the face of this decline, have now joined the slide. In contrast, Darwin (+0.8%) and Hobart (+0.1%) still managed to post slight monthly gains. Capital city auction clearance rates have rebounded somewhat to post an 11-week high of 55.1% for the week ending August 9th, having fallen to a low of 47.4% for the week ending June 21st. However, this remains well below the decade's average preliminary clearance rate of 68%.
Source: Cotality HVI, 01 June 2026 Funds operated by this manager: ASCF Select Income Fund , ASCF High Yield Fund , ASCF Premium Capital Fund , ASCF Private Fund (Wholesale)
|

31 Aug 2026 - Performance Report: Bennelong Twenty20 Australian Equities Fund
[Current Manager Report if available]

28 Aug 2026 - Hedge Clippings | 28 August 2026
|
|
|
Hedge Clippings | 28 August 2026 This week: Sticky inflation keeps the RBA's boot on the throat of leveraged borrowers, and a $3.2 billion Sydney developer which finally buckled under a mountain of debt leads to private credit funds restricting redemptions. Trimmed mean stuck at 3.6% for a third month The July CPI data surprised consensus expectations, but broadly matched those of Seed Funds Management's Nick Chaplin. Headline inflation eased to 3.5% from 3.8% in June, above the 3.2-3.3% consensus, while trimmed mean inflation held at 3.6% for a third month. Chaplin said forecasts underweighted the partial reversal of fuel excise relief, with automotive fuel prices rising 7.5% in July, alongside persistent rental inflation. Three of the big four banks now expect the RBA to raise rates by 25 basis points in September, with another increase possible before Christmas. Chaplin argues the RBA should instead raise rates by 40 basis points on 29 September, given inflation has remained above the 2-3% target band for more than four years. Chaplin also questioned whether the 4.5% unemployment rate fully reflects private-sector labour conditions given rising government employment, suggesting the RBA has greater scope to tighten. In his view, returning inflation to target may require weaker economic conditions, with property a likely pressure point. The bottom line is that the RBA hasn't taken the hard decisions required to bring inflation back into their target band, seemingly hoping that "talk the talk" will work more than having to "walk the walk". Currently, the RBA is not expecting their strategy to succeed until late next year or maybe they're hoping the government's taxation changes will do the job for them, while not wanting to say so publicly. Whether or not the RBA agrees with Chaplin's 40 basis point prescription, the property market is already doing some of the tightening for it. Bathla Group's $3.2 billion in debt finally gave way As has been well reported in the AFR and financial news sites, Bathla Group, a family-owned Western Sydney developer founded in 1997, entered voluntary administration on 25 August. The bottom line is that it owes most of its $3 bn plus debt to private credit funds rather than banks. Bathla now joins Jon Adgemis, whose hospitality operation collapsed in November 2024 with over $1.8 bn in debt, much of it from private credit funds, as a major problem for the private credit sector and its investors. ASIC now warns of "the first significant cracks" in Australian private credit According to per EY estimates, Australia's private credit market has grown from around $35 bn in 2015 to roughly $213 bn by the end of 2024, a more than sixfold expansion that has outpaced the market's exposure to a genuine credit cycle until now. ASIC has been concerned for some time about Private Markets, and the Private Credit sector in particular. The response is now visible across the sector with an increasing number of Australian non-bank lenders, including Merricks, Longreach Credit, Centuria Bass and CVS Lane, restricting investor redemptions as they run into their own liquidity constraints. The problem for the Private Credit sector as a whole is the risk of "redemption contagion" as evidenced by ASX listed MA Financial announcing this week that redemptions from one of their funds would be limited to 1% per month. Although property debt makes up a significant component of the sector, private credit covers a wide range of underlying assets as well as property, including corporate loans, and equipment and asset backed lending. Simply put, not all private credit is the same. Many funds specifically exclude lending for property or property development from their investment mandate. However, they still face the risk of redemptions either through investor misunderstanding the underlying assets, or those redeeming from an open fund simply because they need to, and can't access their investment in a restricted fund. Alternatively, some will make a general move to cash or more liquid listed assets simply as a precaution. While it is prudent for a manager to retain a sensible level of cash to provide liquidity for redemptions, the amount has to be carefully managed. Too much can lead to a "cash drag" on performance, while too little risks imposing restrictions, as are being experienced at present. For the investor there are some basic rules of investing in private credit and private markets in general:
This is exactly the risk highlighted in the FundMonitors Income and Credit review: appraisal-priced credit can report Sharpe ratios above 12 because infrequent valuations suppress reported volatility. A redemption run exposes the gap between reported smoothness and actual liquidity risk. News | Insights Expert Analysis of Australia's July CPI Result Manager Insights | Coller Capital July 2026 Performance News Bennelong Emerging Companies Fund |
|
|
If you'd like to receive Hedge Clippings direct to your inbox each Friday |

28 Aug 2026 - Performance Report: DAFM Digital Income Fund (Digital Income Class)
[Current Manager Report if available]

28 Aug 2026 - Does it fit? A tailored approach to sustainable investing in the apparel industry

27 Aug 2026 - Performance Report: ASCF High Yield Fund
[Current Manager Report if available]

27 Aug 2026 - Manager Insights | Coller Capital
|
Chris Gosselin, CEO of FundMonitors.com, speaks with David Hallifax, Head of Australia & NZ Private Wealth Distribution at Coller Capital. They discuss how private-market secondaries provide liquidity, diversification and access to established private equity and credit assets, as well as how Coller Capital's Australian strategy is structured for private wealth investors. |

26 Aug 2026 - Performance Report: Insync Global Quality Equity Fund
[Current Manager Report if available]

25 Aug 2026 - Performance Report: Bennelong Emerging Companies Fund
[Current Manager Report if available]

.png)