NEWS

16 Sep 2026 - Beyond the hyperscaler: why data centre financing is a project, not a proxy
|
Beyond the hyperscaler: why data centre financing is a project, not a proxy abrdn September 2026 (3-minute read) Artificial intelligence (AI) is often framed as a software story. Yet what is unfolding looks increasingly like an infrastructure boom. Data centres sit at the centre of this buildout, housing the computing infrastructure needed to train, deploy and scale AI models. Like railways, power grids and telecommunications networks before them, they form part of the essential infrastructure on which a broader economic transformation depends. A new frontier for private creditFor private credit investors, this is creating a compelling opportunity in specialist asset-based finance. As demand for AI infrastructure grows, financing markets are evolving to support projects that are larger and more complex than traditional digital infrastructure investments. What is emerging is more than a larger market for lending. It is a specialist asset class bringing together elements of corporate credit, infrastructure, real estate, structured credit and project finance. While hyperscalers remain among the strongest corporate credits globally, the scale of planned investment means funding is increasingly being sourced from a broader range of capital providers. Tailored structures, higher yieldsJoint ventures, project-finance-style vehicles, structured financings and bespoke asset-based arrangements are becoming more common as borrowers and investors seek tailored solutions suited to individual projects. Data centre finance therefore provides a useful lens through which to view the future of private credit: specialist areas where structuring expertise, underwriting skill and tailored capital solutions can create value. These financings often provide exposure to long-term contractual cash flows supported by high-quality hyperscaler counterparties, but with higher yields than debt issued directly by the same companies. At first glance, many appear straightforward: tenant or guarantor exposure plus an additional yield spread. Public-market pricing often reflects this view, with spreads closely linked to those of the underlying counterparty. The additional yield is often viewed as compensation for complexity and reduced liquidity, rather than materially different credit risks. Data centre finance is project finance, not hyperscaler creditHowever, these are ultimately asset-based project financings, not corporate financings. Many structures are designed to transfer substantial construction, operational, power-supply, contractual and leasing risks to the hyperscaler, but those risks are never eliminated entirely. They can be reallocated, mitigated and managed through contractual arrangements, including triple-net leases with floor rent, residual-value guarantees, construction protections, date-certain rent commencement, debt-service reserves and debt that fully amortises within the initial lease term. Even so, the risks remain present to varying degrees. The fact that these financings typically do not carry the same credit ratings as the underlying hyperscalers illustrates the point. If they were equivalent exposures, they would have identical credit ratings. Instead, their ratings are typically heavily influenced by the hyperscaler's credit quality but generally sit below it to reflect the specific risks of the project. Why project structure drives outcomesIn our view, the most important question in data centre finance is what risks sit between the tenant and the lender. Answering that requires understanding how each project allocates risk. Construction risk, power availability, operating performance, contractual protections, refinancing structures, insurance arrangements and long-term asset competitiveness can all influence outcomes. In some transactions, underwriting may also depend on future refinancing conditions, or on the ability to renew and re-lease capacity once existing contracts expire. No two data centre financings are the same. Even two data centres underpinned by the same hyperscaler may transfer and mitigate risks in different ways, resulting in different risk-return profiles. Dispersion creates opportunities for specialist managersMarkets often treat new asset classes as relatively homogeneous in their early stages. Yet history suggests that, over time, differences in structure, underwriting quality and risk allocation become more important drivers of performance. Data centre finance appears unlikely to be an exception. As the sector matures, performance is likely to become more differentiated across projects. In a market characterised by bespoke structures, dispersion is to be expected. For skilled investors, that dispersion creates the opportunity to outperform. Capturing that opportunity requires robust manager selection and underwriting discipline. Understanding the creditworthiness of the hyperscalers supporting these projects remains essential. Investors need a view on the competitive position, financial strength and long-term prospects of the companies driving AI infrastructure demand. But that alone is insufficient. Underwriting these transactions requires expertise across corporate credit, project finance, infrastructure, real estate and structured credit. Depending on the transaction, sustainability factors may also be material to long-term asset resilience and downside risk. The strongest managers are likely to look beyond tenant or guarantor quality to assess whether the compensation offered is sufficient for the risks embedded in each project. The challenge is understanding which risks are being transferred, which risks are being retained and whether investors are being compensated appropriately. Investment discipline mattersThe AI infrastructure buildout is likely to create opportunities for many years to come. The challenge for investors is identifying which opportunities offer the most attractive risk-adjusted returns. Successful managers will need to ensure they are compensated for complexity, illiquidity and the project-specific risks that distinguish these investments from direct exposure to debt issued by the underlying hyperscalers. In our view, success in specialist asset-based private credit, including data centre financing, depends on maintaining a disciplined and selective approach, underpinned by transparency and strong governance in how each transaction is assessed and structured. The ability to say 'no' can be just as important as the ability to say 'yes'. Some opportunities may appear compelling at first glance but still fall short on closer inspection. The project structure may not be sufficiently robust, or the additional spread may not adequately compensate for incremental risks beyond those associated with the underlying hyperscaler. The most successful investors will not be those who finance the most projects, but those with the discipline to walk away from the wrong ones and the patience to wait for the most compelling opportunities. |
|
Funds operated by this manager: abrdn Sustainable Asian Opportunities Fund , abrdn Emerging Markets Equity Fund , abrdn Sustainable International Equities Fund , abrdn Global Corporate Bond Fund (Class A) |

volatile, with ~60% of companies moving more than 5% on
the day of reporting. (2-minute read)
15 Sep 2026 - Glenmore Asset Management - Market Commentary
|
Market Commentary - August Glenmore Asset Management September 2026 (2-minute read) As is usually the case, the August 2026 reporting season was volatile, with ~60% of companies moving more than 5% on the day of reporting. In saying that, results generally proved to be better than expected, with the ASX All Ords Acc Index rising +1.9% during the month. Broadly speaking, stronger profitability margins helped to offset softer sales results. From sector perspective, resources were a clear stand-out (+11.4%), buoyed by strong commodity prices, whilst companies exposed to infrastructure investment, mining services and data centre expenditure also performed well. On the other hand, the impact of higher interest rates and changes to the Federal budget created strain upon both the housing market and consumer spending, weighing upon banks (-6.7%) and consumer discretionary (-10.6%). We note that the July inflation data (released late August) came in higher than forecast, increasing the chances of a rate hike later this calendar year. US equity markets rebounded from a weak July, with the S&P 500 and NASDAQ finishing +2.6% and +3.9%, respectively. This came despite continued bond market volatility and wariness regarding the returns being generated from the enormous amount of AI-related capex. Outside of the US, the Euro Stoxx 50 (+1.0%) and FTSE 100 (-0.4%) underperformed the US and Australian benchmarks. In bond markets, the US 10-year bond yield rose +2bps to 4.75%. Its Australian counterpart rose more sharply, increasing +17bps to 5.1%. The Australian dollar climbed to US$0.72, implying an increase of 1.5 cents. Funds operated by this manager: |

11 Sep 2026 - The AI capex cycle: Is the music still playing?

10 Sep 2026 - The Crowd Is Always Right... Until It Isn't
|
The Crowd Is Always Right... Until It Isn't East Coast Capital Management September 2026 3-minute read In June, the Kospi peaked above 9,300 points. It had risen 76% in 2025. It then doubled again in the first half of this year. Retail investors piled in. Leveraged single-stock ETFs on Samsung and SK Hynix launched in late May, letting them magnify their bets. Then July happened. The Kospi fell 22%. It was the index's worst month since the Global Financial Crisis. Investors who bought the leveraged ETFs near the top and held to mid-July lost about half their money. It is tempting to read this as a story about Korean retail investors and single-stock leverage. It isn't. It is a story about human behaviour, and it repeats in market after market, time after time. The pull of the crowdHerding is not a story about poor judgement. It is a story about a very human need for safety, playing out in markets. Devenow and Welch's 1996 review of the herding literature sets out two distinct versions of the same behaviour. The first is rational herding, where investors copy others because they assume the crowd has information they don't. Each new buyer adds a little more apparent confirmation, and the move builds on itself rather than on fresh evidence. The second is irrational herding, where investors follow the crowd simply because it feels safer, independent of any information content at all. Both versions are underpinned by the same need: safety in numbers. Being wrong alongside everyone else feels different to being wrong alone, whether or not there's a good reason for the crowd to be right. The problem is that this feeling of safety and the actual level of risk move in opposite directions. The more crowded the trade becomes, the more comfortable it feels, and the more fragile it actually is. Two versions of the same patternThe Kospi shows the sharp version. A fast, leveraged, retail-driven move that unwound just as quickly. FOMO plus leverage plus a crowded trade is a well-worn combination, and it tends to end the same way. Precious metals show the slower version. Gold and silver's move over 2024 and 2025 was driven by real forces: central bank buying, rate expectations, currency dynamics. But the story around the move was also self-reinforcing. Rising prices attract new buyers, media coverage amplifies the narrative, and at some point the narrative itself becomes a reason to buy, separate from the fundamentals that started it. This is a genuine multi-year trend, not a single blow-off. That is precisely why it is a better test of discipline than a bubble is. Staying in a strong trend is not the mistake. Staying in without any plan for managing the position is. Where trend following fitsTrend following is a way to trade that behaviour rather than get caught in it. Price sets the entry and the exit. That's what makes it possible to be in a crowded trade without being trapped by it. Trend following looks for trends early, often before they're conspicuous, and stays with them as the crowd arrives. The Kospi's move and the precious metals run are both trades our systematic models identified before either became a mainstream story. Herding is fuel. The buying that pushes a trend from early to obvious, and then from obvious to crowded, is exactly what a trend-following strategy is designed to capture. Systematic trend following sizes positions based on volatility, not conviction. When its indicators show the trend is no longer there, it exits. There's no leverage stacked on top of an already extended move. A system does not need to keep believing in a story to justify staying in. It also has no memory of its own trades. It doesn't hold on because admitting the trend has turned feels like admitting a mistake. A system has no ego invested in being right, so it has no reason to ignore what the price is doing. That is the real distinction. Not whether to participate in a trend, but how early the position was built, and how quickly it is closed once the trend ends. The Kospi and precious metals weren't failures of the crowd, or of the trend. Herding will keep shaping markets. What matters is having a process for participating in it. Funds operated by this manager: This article contains general information only and does not take into account the objectives, financial situation or needs of any individual. It is not intended as investment advice, and nothing in this article constitutes an offer to invest. The ECCM Systematic Trend Fund is available to wholesale clients only, as defined under the Corporations Act. Past performance is not a reliable indicator of future performance. |

9 Sep 2026 - New Funds on Fundmonitors.com
| New Funds on FundMonitors.com | ||||||||||||||||||||||
|
Below are some of the funds we've recently added to our database. Follow the links to view each fund's profile, where you'll have access to their offer documents, monthly reports, historical returns, performance analytics, rankings, research, platform availability, and news & insights. |
||||||||||||||||||||||
 |
||||||||||||||||||||||
| Perennial Private to Public Evergreen Fund | ||||||||||||||||||||||
|
||||||||||||||||||||||
| View Profile | ||||||||||||||||||||||
|
Perennial Future of Healthcare Fund |
||||||||||||||||||||||
|
||||||||||||||||||||||
|
|
||||||||||||||||||||||
 |
||||||||||||||||||||||
| Collins St Global Fund | ||||||||||||||||||||||
|
||||||||||||||||||||||
| View Profile | ||||||||||||||||||||||
 |
||||||||||||||||||||||
| OC Mid-Cap Fund | ||||||||||||||||||||||
|
||||||||||||||||||||||
| View Profile | ||||||||||||||||||||||
|
Want to see more funds? |
||||||||||||||||||||||
|
Subscribe for full access to these funds and over 1100 others |

8 Sep 2026 - Infrastructure in focus: The burning infrastructure issue from wildfires

4 Sep 2026 - Proof points: AI leaves its mark on corporate earnings
|
Proof points: AI leaves its mark on corporate earnings Janus Henderson Investors August 2026 (7-minute read) Artificial Intelligence remains the dominant force in global equity markets. Investors are captured by the growing capabilities of the most advanced frontier AI models. Meanwhile, the unprecedented scale - and price tag - of the AI infrastructure buildout continues to be a flashpoint, dividing AI optimists and those concerned about whether future returns will ultimately justify this level of investment. Neither of these headline grabbers can be looked upon in isolation. Instead, investors must understand that these developments share a common objective: to fundamentally transform the way work is conducted across the global economy. More than words: Judging companies on their results Early in the AI era, exactly how this revolutionary technology would be deployed and the degree to which it would enhance productivity were largely matters of conjecture. That is no longer the case. The recently concluded earnings season provides quantifiable evidence that AI is delivering on its ambitious promise. Importantly - and in contrast to recent quarters - management commentary has shifted from AI adoption metrics to AI financial results. Areas in which executive teams highlight AI's financial impact include operating margins, productivity gains, revenue generation, and even physical workflows. And while tech companies, with their emphasis on coding, and industrial concerns, given their headstart in automation, are at the forefront of AI adoption, healthcare, financial, consumer, and materials firms are also reporting how integrating this technology contributes to their bottom line. This dispersion of AI efficiencies is no surprise to us. We've spoken previously of AI enablers, enhancers, and end users. Given the backlog of AI infrastructure initiatives, the enablers - led by hyperscalers - are still a major part of the story. But the other two categories have now entered the conversation. This, in our view, has major investment implications, as 1) not all companies will have the same level of success in adopting AI and 2) as was illustrated during the digital revolution a quarter century ago, the greatest share of economic gains was generated by novel technologies' end users. We believe we are on the cusp of a similar transition. Watching margins To gauge AI's financial impact on the corporate sector, we deployed - not by coincidence - an AI model to scour the recent earnings reports of 109 listed companies. Of those, 69% disclosed some degree of margin improvement due to productivity gains and AI-associated cost reductions. While the rate of margin improvements did not surprise us, in many instances the scale did. IBM, for example, stated it realized $4.5 billion in AI-related savings in 2025. As is the case with other companies, IBM has grown more confident in referencing AI in company guidance: the company is targeting these savings to reach $5.5 billion in 2026. Within financials, PayPal is guiding the street toward an expectation of $1.5 billion in run-rate savings, with most driven by AI. Margin improvement is coming in the form of both operating leverage (Alphabet reports roughly 50% of its internal software code is written by AI agents) and declining product development expense, as illustrated by MercadoLibre reporting that line item has declined by 120 basis points (bps), year over year. These examples highlight the trend that much of the cost savings is occurring within the tech (coding) and customer service functions. MercadoLibre also announced a 90% resolution rate in AI-based customer service interactions. Building on its foundation of machine learning, AI is now reaching the factory floor and mining operations. In one of its facilities, Hitachi reduced inventory held by 50% and lead times by 77%. Copper miner Freeport McMoRan reported increasing mill throughput by 10% while reducing unit costs by up to 15%. Within the energy space, Shell announced $400 million in annual savings and reduced unplanned downtime by 45%. The top line gets involved It's not just margins that are providing an AI-powered lift to earnings. Within our data set, 26% of companies discussed AI's impact on revenue growth, with most operating digital platforms in the tech and consumer space. One development highlighted by several companies is digital assistants materially contributing to sales growth. Amazon's assistant, for example, was credited with $12 billion in incremental annual retail sales, and Walmart reported that orders utilizing its shopping assistant were 35% larger than those that did not. Platforms in which advertising comprises a significant contribution to revenue also indicated that AI improved results. In a telling example, Alphabet's AI Max tool was stated to have increased conversion volume by 15%. On the buyer side, Proctor & Gamble's Auto-Bidder system adjusts ad-bids every 15 minutes in response to real-time retail data. The upshot, according to the company, is a four-fold higher return on its branded sales compared to legacy static bidding. Working smarter Many of the workflows likely affected by AI tend to have a large human element. While productivity may be defined as doing more with less, thus far AI is delivering more with the same. Several companies in our data set reported growth while keeping headcount flat. Commentary reveals that AI has been most effective when being applied to repetitive or high-volume tasks. This is freeing up companies to reallocate labor to more value-added work. Many companies have slowed incremental hiring, and there have been layoffs, but this is evidence of the emerging trend of growth decoupling from headcount. An example is JPMorgan expecting to reduce consumer banking headcount 10% by 2030 while growing the business 25%. Across sectors, companies reported a shift from limited pilot programs to increasing licenses across their workforce. While these initiatives are showing up in company financials today, other AI applications are aimed at delivering economic value in the future. Pfizer, for example, stated it expects AI integrated into drug discovery, clinical trials, and manufacturing to increase enterprise value by up to $4 billion over the mid term. Acting on the evidence We view these examples as just the beginning. Other AI enhancers and end users will invariably apply the technology in innovative and unique ways. The cadence and breadth of the rollout, in our view, have significant investment implications. Early movers have the potential to gain an advantage over slower-acting peers. Some management teams will underestimate AI's potential for disruption and be left behind. We expect future earnings seasons to shed additional light on this dispersion. For the first time, investors have the opportunity to analyze real data to gauge AI's financial impact. Given our ethos that equities follow earnings, we believe investors should seek to identify the companies that can translate AI deployment to top-line growth, margin expansion, and ultimately higher earnings. And it's not only equities markets where AI is a driving - and differentiating - force. Improving margins should be on bond investors' radar as well, as they may improve the coverage ratios of AI-forward companies. Conversely - and given the magnitude of the AI investment cycle - the hyperscalers that deliver the best value proposition to their customers are likely better positioned to generate the cash flows to pay down debt, while those employing less effective strategies may be left with overleveraged balance sheets. |
|
Funds operated by this manager: Janus Henderson Australian Fixed Interest Fund , Janus Henderson Conservative Fixed Interest Fund , Janus Henderson Diversified Credit Fund , Janus Henderson Global Natural Resources Fund , Janus Henderson Tactical Income Fund , Janus Henderson Australian Fixed Interest Fund - Institutional , Janus Henderson Conservative Fixed Interest Fund - Institutional , Janus Henderson Cash Fund - Institutional , Janus Henderson Global Multi-Strategy Fund , Janus Henderson Global Sustainable Equity Fund , Janus Henderson Sustainable Credit Fund All opinions and estimates in this information are subject to change without notice and are the views of the author at the time of publication. Janus Henderson is not under any obligation to update this information to the extent that it is or becomes out of date or incorrect. The information herein shall not in any way constitute advice or an invitation to invest. It is solely for information purposes and subject to change without notice. This information does not purport to be a comprehensive statement or description of any markets or securities referred to within. Any references to individual securities do not constitute a securities recommendation. Past performance is not indicative of future performance. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested. Whilst Janus Henderson believe that the information is correct at the date of publication, no warranty or representation is given to this effect and no responsibility can be accepted by Janus Henderson to any end users for any action taken on the basis of this information. |

3 Sep 2026 - A Growing Market Under Greater Scrutiny
|
A Growing Market Under Greater Scrutiny Challenger Investment Management August 2026 (6-minute read) Commercial real estate debt has moved firmly into the spotlight. Recent reporting on borrower stress, loan defaults, enforcement activity and related-party lending have brought greater scrutiny to lending practices across the sector. While the circumstances differ, the headlines have sharpened investor focus on the risks beneath the broad CRE debt label. Security Is Only the Starting PointCRE debt has become a growing allocation within Australian private debt portfolios. The appeal is clear: loans are generally secured by physical assets, have relatively short tenors, pay floating-rate interest and often incorporate structural protections tailored to the individual transaction. Together, these features can provide attractive risk-adjusted income and meaningful downside protection. But the protection is only as strong as the underwriting that supports it. Testing the AssumptionsThe starting principle is simple: the underwrite must inform the price, leverage and structure of the loan, not be reverse engineered to support terms already proposed. That requires a qualitative assessment of the sponsor's experience, financial capacity, track record and alignment, together with a clear understanding of the property, its competitive position and the credibility of the business plan. Finding the Margin for ErrorThe real value of underwriting lies in identifying the loan's margin for error. A base case may show that the borrower's strategy can succeed, but not how the loan performs when assumptions move adversely. The analysis should extend beyond a single forecast to test how changes in cash flow, valuation, debt accretion and exit liquidity interact. Four variables are particularly important: Capitalisation rates Capitalisation rates are a key driver of property value, particularly where income has not yet stabilised. Even a modest increase can materially reduce value and increase leverage. The underwrite should therefore test exit values under different interest-rate, property-risk and investor-demand assumptions, rather than relying on current capitalisation rates persisting. Net income Property income is primarily influenced by occupancy, rents, incentives and operating costs. Rents may remain stable while effective rents decline as incentives or landlord contributions increase. Rising non-recoverable costs, such as insurance premiums and land tax, can adversely impact income and value. Leasing Longer lease-up periods delay rental income, increase interest reserve usage and may require additional capital incentives. This can increase debt at the same time as the delayed income reduces collateral value, compounding the effect on leverage. The underwrite should also test whether leases can be renewed on acceptable terms when they expire. Capital leakage Make-good costs, leasing fees, tenant works and interest shortfalls consume liquidity before they contribute to property value. Sensitivity analysis should test whether available reserves are sufficient and whether further delays or costs cause interest to capitalise, debt to increase and the lender's equity cushion to erode. A single downside LVR (Loan to Value Ratio) does not tell the full story. The analysis should show how the loan deteriorates under stress, which assumptions drive that deterioration and how much protection remains when multiple variables move adversely together. Heat maps, breakeven analysis and scenario tables all help identify these pressure points and assist in determining the appropriate leverage, pricing and loan structure. Turning Expectation into ObligationUnderwriting identifies where a loan may come under pressure. Structuring determines the lender's protections and options when it does. Covenants, review events, cash controls, reserve accounts, reporting requirements, leasing and/or selling milestones and valuation triggers provide early warning of emerging risks and give the lender an opportunity to act before value materially deteriorates. Early intervention increases the range of constructive solutions available to preserve value and support an orderly resolution. For investors, the relevant question is not simply whether a loan is secured by real estate, but how that security performs when the borrower's strategy falls short. The underwriting process should address that question before the loan is made, translating into appropriate leverage, pricing and structural protection. In CRE debt, the quality of the outcome is determined long before the downside arrives. Challenger IM Credit Income Fund , Challenger IM Multi-Sector Private Lending Fund For Adviser & Investors Only Disclaimer: This material has been prepared by Challenger Investment Partners Limited (Challenger Investment Management or Challenger), ABN 29 092 382 842, AFSL 329 828. This document does not relate to any financial or investment product or service and does not constitute or form part of any offer to sell, or any solicitation of any offer to subscribe or interests and the information provided is intended to be general in nature only. This should not form the basis of, or be relied upon for the purpose of, any investment decision. This document is not available to retail investors as defined under local laws. This document has been prepared without taking into account any person's objectives, financial situation or needs. Any person receiving the information in this document should consider the appropriateness of the information, in light of their own objectives, financial situation or needs before acting. This document is provided to you on the basis that it should not be relied upon for any purpose other than information and discussion. The document has not been independently verified. No reliance may be placed for any purpose on the document or its accuracy, fairness, correctness, or completeness. Neither Challenger Investment Management nor any of its related bodies corporates, associates and employees shall have any liability whatsoever (in negligence or otherwise) for any loss howsoever arising from any use of the document or otherwise in connection with the presentation. |

(5-minute read)
2 Sep 2026 - Why Warren Buffett waits for the fat pitch
|
Why Warren Buffett waits for the fat pitch Marcus Today August 2026 5-minute read Warren Buffett borrowed the fat pitch idea from a baseball legend, and it might be the simplest investing lesson there is. The origins of the fat pitchThe original idea of the Fat Pitch approach came from Ted Williams, a Boston Red Sox hitter, in his 1970 book The Science of Hitting. Williams carved the strike zone into seventy-seven squares, each the size of a baseball, and worked out his batting average for each one. In his best squares he hit around .400. In the low outside corner he hit around .230. His discipline was simple - only swing at balls in the good squares, and let the rest go by even if that meant taking strikes.
Why investors have it easier than battersBuffett took this and pointed out the bit that makes it better for investors than for batters. In baseball, you get called out on three strikes. In investing, there are no strikes. Nobody forces you to swing. You can stand there with the bat on your shoulder for months or years while thousands of pitches go past, and the only penalty is that nothing happens. So you wait for the fat pitch - the one that is slow, in the middle, and obviously mispriced - and then you swing hard and big. Swinging big is an important element - if you are going to ignore a lot of possible opportunities, then the easy ones you have to hit a lot harder. What this means for investorsWhat it means for an investor.
The punch card variantCharlie Munger said the trick is not being smarter than everyone else; it is being able to sit on your backside and do nothing for very long stretches without getting bored. Buffett added the Punch Card variant - he said, imagine you get a card with twenty punches on it for your whole investing life, one punch per decision, and when it runs out you are done. He reckoned you would make much better decisions and end up much richer. |
|
Funds operated by this manager: |


1 Sep 2026 - Australian Secure Capital Fund - Property Update
|
Australian Secure Capital Fund - Property Update Australian Secure Capital Fund August 2026 (1-minute read)
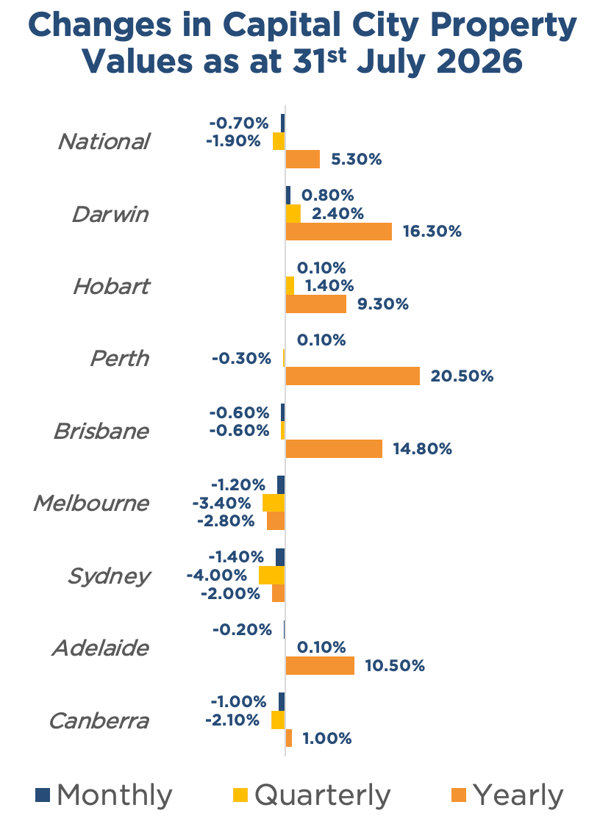
July continued the recent trend of declining Australian property values with a -0.7% monthly decrease. This marks the third consecutive monthly decline, and the largest single-month decline in Australian property values since December 2022. Sydney (-1.4%) and Melbourne (-1.2%) still lead the way in this regard, posting their sixth consecutive monthly declines. Even the mid-sized capitals of Perth (-0.3%), Adelaide (-0.2%), and Brisbane (-0.6%), which had previously been resilient in the face of this decline, have now joined the slide. In contrast, Darwin (+0.8%) and Hobart (+0.1%) still managed to post slight monthly gains. Capital city auction clearance rates have rebounded somewhat to post an 11-week high of 55.1% for the week ending August 9th, having fallen to a low of 47.4% for the week ending June 21st. However, this remains well below the decade's average preliminary clearance rate of 68%. 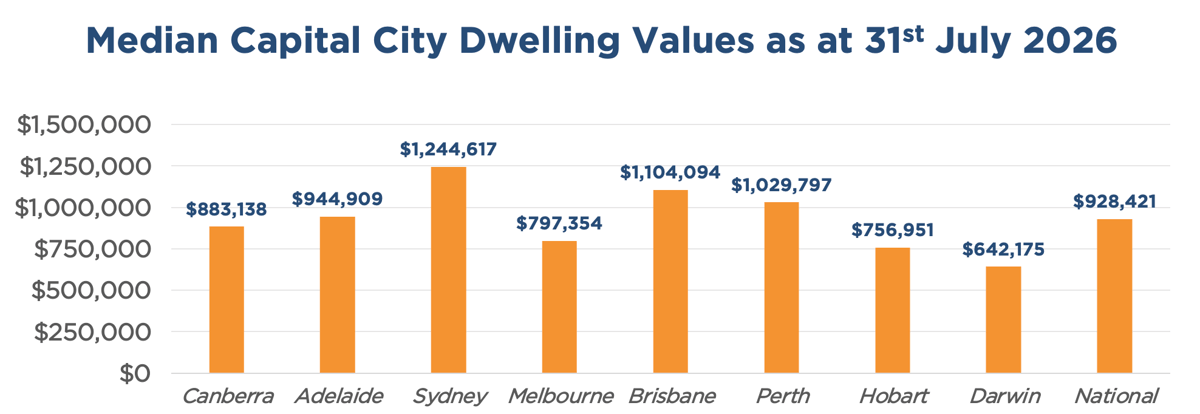
Source: Cotality HVI, 01 June 2026 Funds operated by this manager: ASCF Select Income Fund , ASCF High Yield Fund , ASCF Premium Capital Fund , ASCF Private Fund (Wholesale)
|